🎯 Introduction
Getting approved for a credit card in 2026 is more streamlined than ever, thanks to advances in digital banking, automated underwriting systems, and financial technology. The credit card approval process has evolved significantly, incorporating artificial intelligence, machine learning algorithms, and real-time verification systems. However, approval still depends on several key factors that lenders evaluate.
Whether you’re a first-time credit applicant, credit rebuilder, or looking to expand your credit portfolio, this comprehensive guide will walk you through the essential steps to maximize your chances of approval and help you understand the modern credit card approval process in detail. How to Get Approved for a Credit Card Easily in 2026
The credit card landscape has evolved significantly, with financial institutions now utilizing sophisticated artificial intelligence systems and machine learning models to assess creditworthiness more accurately. Understanding these changes and preparing accordingly is crucial for success.
Table of Contents
1️⃣ Check and Improve Your Credit Score
Understanding Credit Score Semantics and Related Entities
Your credit score is unquestionably the primary factor lenders consider when evaluating your credit card application. This three-digit numerical representation (ranging from 300 to 850) reflects your creditworthiness and credit history.
Entity Relationships:
Credit Score
├── Components
│   ├── Payment History (35%)
│   ├── Amounts Owed/Utilization (30%)
│   ├── Credit History Length (15%)
│   ├── New Credit Inquiries (10%)
│   └── Credit Mix (10%)
├── Factors
│   ├── Credit Bureau Data
│   ├── Lender Reports
│   └── Payment Behavior
├── Range Categories
│   ├── Poor (300-579)
│   ├── Fair (580-669)
│   ├── Good (670-739)
│   ├── Very Good (740-799)
│   └── Excellent (800-850)
└── Impact
    ├── Approval Chances
    ├── Interest Rates
    └── Credit Limits
🔍 Why Your Credit Score Matters
In 2026, most traditional credit cards require a minimum credit score of at least 620, while premium credit cards and rewards cards may require significantly higher scores of 750 or above. Your credit score is essentially a numerical representation of your creditworthiness, based on your credit history, payment patterns, and overall financial behavior.
A strong credit score demonstrates to lenders that you have a proven track record of managing credit responsibly. The three major credit reporting agencies—Equifax, Experian, and TransUnion—maintain these scores based on information reported by creditors and financial institutions.
Semantic Connection: The relationship between credit scores and credit approval creates a transactional entity—lenders use credit bureau data to calculate scores, which directly determine approval likelihood.
📈 How to Improve Your Credit Score
Strategy 1: Request Your Free Credit Reports
Your credit report contains detailed information about all your credit accounts, payment history, credit inquiries, and any negative items that might affect your score. By law, you’re entitled to one free credit report annually from each of the three major credit bureaus through the official free credit report service.
Semantic Actions:
- Obtain credit reports from: Equifax, Experian, TransUnion
- Review for: Errors, inaccuracies, unauthorized accounts
- Timeline: 30 days before applying for credit
- Frequency: Annually (minimum), quarterly (recommended)
Reviewing these reports is absolutely essential because they often contain errors or outdated information that can negatively impact your score. When you obtain your credit reports, examine them meticulously for any accounts you don’t recognize, payments that were incorrectly marked as late, or duplicate accounts.
Key Entities Involved:
- Inaccuracy (Credit Report Issue)
- Late Payment (Negative Item)
- Duplicate Account (Error Type)
- Dispute Process (Resolution Method)
These errors are more common than you might think, and correcting them can result in immediate score improvements. Take your time reviewing each section of your report:
- Personal information section
- Credit accounts section
- Public records section
- Inquiries section
Strategy 2: Correct Errors Through Disputes
Disputing inaccurate information on your credit reports is one of the most straightforward ways to improve your credit score quickly. This process is called a credit dispute or credit report dispute.
Dispute Process Entities:
Credit Dispute
├── Types
│   ├── Payment Error Dispute
│   ├── Account Status Dispute
│   ├── Identity Theft Dispute
│   └── Outdated Information Dispute
├── Process
│   ├── Identify Error
│   ├── Contact Credit Bureau
│   ├── Submit Documentation
│   ├── Bureau Investigation (30 days)
│   └── Resolution
├── Potential Outcomes
│   ├── Information Removed
│   ├── Information Corrected
│   ├── Information Verified
│   └── Dispute Notation Added
└── Timeline
    ├── 30 days (investigation period)
    ├── 5-7 days (update to report)
    └── 2-4 weeks (score impact visible)
When you identify errors such as:
- Incorrect account statuses
- Erroneous late payments
- Accounts that aren’t yours
- Information from identity theft
You have the right to dispute these items with the credit bureaus. You can initiate disputes online, by mail, or by phone, and the credit bureaus are required to investigate your claims within 30 days.
Semantic Value: The dispute process represents a consumer protection mechanism that directly impacts credit score calculation and approval likelihood.
Strategy 3: Establish Perfect Payment History
Payment History accounts for approximately 35 percent of your overall credit score, making it the single most important factor in credit score calculation.
Payment History Semantic Model:
Payment History
├── Definition
│   └── Record of on-time or late payments
├── Components
│   ├── Account Types (credit cards, loans, utilities)
│   ├── Payment Amounts
│   ├── Payment Dates
│   ├── Days Late (if applicable)
│   └── Current Account Status
├── Impact on Score
│   ├── On-time payment: +points
│   ├── 30-day late: -20-100 points
│   ├── 60-day late: -50-150 points
│   ├── 90+ day late: -75-200 points
│   └── Charge-off/Collections: -100-200 points
├── Retention Period
│   └── 7 years from delinquency date
└── Recovery Timeline
    ├── 30-day impact: Decreases after 3-4 years
    ├── 60-day impact: Decreases after 5-6 years
    ├── 90+ day impact: Decreases after 7+ years
    └── Perfect history: Continuous improvement
This means that consistently making on-time payments for all your financial obligations—credit cards, loans, utilities, and rent—is absolutely critical to building and maintaining a strong credit score. When you make payments on time, it demonstrates to lenders that you’re reliable, trustworthy, and capable of managing financial responsibilities.
Action Items for Payment History:
- Set automatic payments for minimum amount due
- Schedule payments 5-7 days before due date
- Track all payment dates and amounts
- Keep proof of payment for disputes
- Monitor account statements for payment posting
Strategy 4: Optimize Credit Utilization
Credit Utilization (also called credit utilization ratio) refers to the percentage of your available credit that you’re currently using and represents approximately 30 percent of your credit score calculation.
Credit Utilization Semantic Framework:
Credit Utilization Ratio
├── Definition
│   └── (Total Credit Used / Total Credit Available) × 100
├── Calculation Example
│   ├── Scenario: $2,500 balance on $5,000 limit
│   ├── Calculation: ($2,500 / $5,000) × 100 = 50%
│   └── Rating: High (Negative Impact)
├── Recommended Ranges
│   ├── Excellent: 0-5% (Optimal)
│   ├── Very Good: 5-10% (Ideal Target)
│   ├── Good: 10-30% (Acceptable)
│   ├── Fair: 30-50% (Concerning)
│   └── Poor: 50%+ (Harmful)
├── Impact on Score
│   ├── Below 10%: Positive impact
│   ├── 30% or below: Acceptable
│   ├── 30-50%: Slight negative impact
│   └── Above 50%: Significant negative impact
├── Improvement Methods
│   ├── Pay down balances
│   ├── Request credit limit increase
│   ├── Open new credit accounts
│   ├── Become authorized user
│   └── Time payments strategically
└── Reporting
    ├── Updated monthly at statement closing
    ├── All three bureaus receive updates
    └── Changes reflected in 1-2 billing cycles
Utilization Reduction Strategies:
- Payment Timing Strategy
- Make payment 2-3 days before statement closing date
- Reduces reported balance at bureaus
- Full balance payment after closing acceptable
- Credit Limit Increase Strategy
- Request increase (soft or hard inquiry)
- Higher limit = lower utilization percentage
- Same balance = better ratio
- Account Diversification
- Open new credit account
- Spreads debt across multiple accounts
- Increases total available credit
- Results in lower overall utilization
Strategy 5: Manage Credit Inquiries
Hard Inquiries occur when a lender pulls your full credit report as part of an application process, and each hard inquiry can reduce your credit score by 5 to 10 points temporarily.
Credit Inquiry Semantic Structure:
Credit Inquiry Types
├── Hard Inquiry (Negative Impact)
│   ├── Trigger: Credit application
│   ├── Score Impact: -5 to -10 points
│   ├── Duration: 1 year on report, 3-6 months impact
│   ├── Visibility: Shows to other lenders
│   ├── Frequency: Each application counts
│   └── Multiple within 14-45 days: May count as one (for same product type)
├── Soft Inquiry (No Impact)
│   ├── Trigger: Personal checking, account review
│   ├── Score Impact: None
│   ├── Duration: Not visible to lenders
│   ├── Visibility: Only to account holder
│   ├── Frequency: Check as often as desired
│   └── Examples: Credit monitoring, card issuer reviews
└── Inquiry Management
    ├── Space applications by 3-6 months
    ├── Apply only for cards you need
    ├── Check personal score frequently (soft inquiry)
    ├── Consolidate rate shopping (same product type)
    └── Monitor inquiry history
Inquiry Impact Analysis:
Multiple hard inquiries within a short period signal to lenders that you’re desperately seeking credit or that you’ve been denied multiple times, which increases their perception of risk. However, it’s important to understand that multiple inquiries for the same type of credit product (such as credit cards or auto loans) within a 14-to-45-day period typically count as a single inquiry for credit scoring purposes, recognizing that consumers often shop around for the best rates.
2️⃣ Get Your Finances in Order
Financial Health Semantic Framework
Getting your finances in order involves evaluating three critical financial metrics that lenders use to assess your ability to repay credit.
💰 Understand Your Debt-to-Income Ratio
Your debt-to-income ratio (DTI) is a critical metric that lenders examine to determine how much of your monthly income is already committed to debt payments.
DTI Calculation Semantic Model:
Debt-to-Income Ratio (DTI)
├── Formula
│   └── (Total Monthly Debt Payments / Gross Monthly Income) × 100
├── Calculation Example
│   ├── Monthly Debt: $1,500
│   │   ├── Credit card payment: $300
│   │   ├── Car loan: $400
│   │   ├── Student loan: $500
│   │   └── Mortgage: $300
│   ├── Gross Monthly Income: $5,000
│   └── DTI: ($1,500 / $5,000) × 100 = 30%
├── Lender Preferences
│   ├── Excellent: Below 20%
│   ├── Good: 20-36%
│   ├── Acceptable: 36-43%
│   └── Risky: Above 43%
├── Impact on Credit Card
│   ├── Below 28%: Favorable for approval
│   ├── 28-36%: Standard approval range
│   ├── 36-43%: May require additional review
│   └── Above 43%: Likely denial
├── Improvement Strategies
│   ├── Increase Income
│   │   ├── Request promotion
│   │   ├── Start side business
│   │   └── Additional employment
│   ├── Decrease Debt
│   │   ├── Pay down balances
│   │   ├── Pay off small loans
│   │   └── Aggressive loan repayment
│   └── Combination Approach
│       ├── Moderate income increase
│       └── Moderate debt reduction
└── Documentation
    ├── Recent pay stubs
    ├── Tax returns
    ├── Bank statements
    └── Debt statements
DTI Improvement Path:
- Income Documentation
- Gather recent pay stubs (2-3 months)
- Calculate average monthly income
- Include all household income sources
- Document any bonuses or commissions
- Debt Inventory
- List all monthly debt obligations
- Include minimum payments for revolving debt
- Calculate total monthly obligations
- Identify high-interest debts to prioritize
- Strategic Paydown
- Prioritize high-utilization credit cards
- Pay minimum on others while focusing on one
- Make extra payments to reduce balances
- Track DTI improvement monthly
💼 Establish Stable Income and Employment
In 2026, having a steady employment history and consistent income source is crucial for credit card approval, as it demonstrates that you have reliable means to repay any credit extended to you.
Employment Stability Semantic Model:
Employment Stability
├── Key Factors Evaluated
│   ├── Employment Duration
│   │   ├── Current position: 2+ years preferred
│   │   ├── Career field: 2+ years in same industry
│   │   ├── Job changes: Less than 3 within 5 years
│   │   └── Gaps: Explained and reasonable
│   ├── Income Consistency
│   │   ├── Same employer: 2+ years
│   │   ├── Salary progression: Stable or increasing
│   │   ├── Variable income: 2-year average acceptable
│   │   └── Recent raise: Document with offer letter
│   ├── Employment Verification
│   │   ├── Digital verification systems
│   │   ├── Direct employer contact
│   │   ├── Third-party verification services
│   │   └── Employment databases
│   └── Income Documentation
│       ├── Recent pay stubs (30-60 days old)
│       ├── W-2 forms (2 years)
│       ├── Tax returns (2 years)
│       └── Offer letters
├── Employment Types
│   ├── Traditional W-2 Employee
│   │   ├── Easiest to verify
│   │   ├── Most lenders prefer
│   │   └── Standard documentation
│   ├── Self-Employed
│   │   ├── Requires tax returns
│   │   ├── Business financials needed
│   │   └── 2-year history required
│   ├── Commission-Based
│   │   ├── Average income over 2 years
│   │   ├── Recent pay stubs important
│   │   └── Bonus documentation helpful
│   ├── Contract/Temporary
│   │   ├── Job security concerns
│   │   ├── Contract terms needed
│   │   └── More difficult to approve
│   └── Retired/Pension
│       ├── Social Security statements
│       ├── Pension documentation
│       ├── Investment income statements
│       └── Varies by lender
└── Verification Process
    ├── Automated verification
    ├── Direct verification
    ├── Database verification
    └── Manual verification
Income Verification Strategies:
- Traditional Employment
- Provide 2-3 recent pay stubs
- Include W-2 or tax return
- Contact information for employer
- Length of employment documented
- Self-Employment/Business
- 2 years of tax returns
- Recent business bank statements
- Profit and loss statements
- Separate business account from personal
- Variable Income
- Calculate 2-year average
- Document income sources
- Show recent deposits
- Explain income fluctuations
🏦 Build and Maintain Emergency Savings
Having emergency savings demonstrates to lenders that you have financial responsibility and a cushion to handle unexpected expenses without relying on credit.
Emergency Savings Semantic Framework:
Emergency Savings
├── Recommended Amounts
│   ├── Minimum: 3 months of expenses
│   ├── Optimal: 6 months of expenses
│   ├── Comprehensive: 12 months of expenses
│   └── Calculation: Essential expenses × Months
├── Impact on Approval
│   ├── No savings: Negative perception
│   ├── 1-2 months: Minimal positive impact
│   ├── 3-6 months: Moderate positive impact
│   ├── 6-12 months: Strong positive impact
│   └── 12+ months: Excellent perception
├── Account Types
│   ├── High-yield savings account
│   │   ├── Interest earned: 4-5% APY
│   │   ├── Liquidity: Instant access
│   │   └── Security: FDIC insured
│   ├── Money market account
│   │   ├── Higher yields
│   │   ├── Check writing capability
│   │   └── Minimum balances required
│   ├── Regular savings account
│   │   ├── Minimal interest
│   │   ├── Accessible
│   │   └── FDIC protected
│   └── Certificate of deposit
│       ├── Locked funds
│       ├── Higher interest rates
│       └── Not ideal for emergency funds
├── Building Strategy
│   ├── Automatic transfers (bi-weekly)
│   ├── Round-up apps (automatic savings)
│   ├── Tax refunds (annual deposits)
│   ├── Bonuses (direct to savings)
│   └── Percentage of income (10-20%)
├── Lender Considerations
│   ├── Account age (longer better)
│   ├── Account activity (regular deposits)
│   ├── Account balance (minimum thresholds)
│   ├── Account type (linked to primary bank)
│   └── Account verification (during application)
└── Financial Resilience
    ├── Reduced credit card reliance
    ├── Ability to handle emergencies
    ├── Better credit score management
    ├── Lower stress and anxiety
    └── Improved financial outcomes
Savings Building Approach:
- Assessment Phase
- Calculate monthly essential expenses
- Determine savings goal (3-6 months)
- Calculate monthly savings needed
- Execution Phase
- Open high-yield savings account
- Set up automatic transfers
- Track progress monthly
- Adjust strategy as needed
- Lender Documentation
- Bank statements showing savings
- Account history and deposits
- Recent transaction records
- Account verification confirmation


3️⃣ Gather Required Documentation
Document Requirements Semantic Structure
Modern credit card applications in 2026 now often require minimal documentation due to advanced digital verification systems, but being prepared with the following items will streamline your application process and ensure you can complete it quickly without delays.
Documentation Requirements Matrix:
Credit Card Application Documentation
├── Identity Verification
│   ├── Government-issued ID
│   │   ├── Driver's license
│   │   ├── Passport
│   │   ├── Military ID
│   │   ├── State ID card
│   │   ├── Requirement: Current/Not expired
│   │   ├── Name match: Must match exactly
│   │   └── Verification method: Photo/video scan
│   └── Social Security Number
│       ├── Purpose: Credit report access
│       ├── Purpose: Identity verification
│       ├── Purpose: Employment verification
│       ├── Requirement: Valid and matching records
│       └── Security: Protect from misuse
├── Income Documentation
│   ├── W-2 Employee
│   │   ├── Recent pay stubs (30-60 days old)
│   │   ├── Employment offer letter
│   │   ├── W-2 forms (past 2 years)
│   │   └── Verification: Employment verification service
│   ├── Self-Employed
│   │   ├── Business tax returns (2 years)
│   │   ├── Current business bank statements
│   │   ├── Profit and loss statements
│   │   └── Verification: IRS records check
│   ├── Variable Income
│   │   ├── Commission statements
│   │   ├── Bonus documentation
│   │   ├── Investment statements
│   │   └── Verification: Account statements
│   └── Other Income
│       ├── Rental income statements
│       ├── Social Security statements
│       ├── Pension documentation
│       └── Investment account statements
├── Address Verification
│   ├── Accepted Documents
│   │   ├── Utility bills (electricity, gas, water)
│   │   ├── Internet/cable bills
│   │   ├── Rental agreement/lease
│   │   ├── Mortgage statement
│   │   ├── Property tax statement
│   │   ├── Bank statements
│   │   └── Insurance statements
│   ├── Recency Requirements
│   │   ├── Within 60 days: Standard
│   │   ├── Within 30 days: Recently moved
│   │   └── Forwarding address: If new
│   └── Address Match
│       ├── Name must match ID
│       ├── Address must be current
│       └── Same address across documents preferred
├── Employment Information
│   ├── Current Employment Details
│   │   ├── Employer name
│   │   ├── Job title/position
│   │   ├── Length of employment
│   │   ├── Employer contact information
│   │   └── Verification method
│   ├── Employment History
│   │   ├── Previous employers (past 2 years)
│   │   ├── Employment dates
│   │   ├── Job transitions explained
│   │   └── Career stability demonstrated
│   └── Contact Verification
│       ├── Direct employer contact
│       ├── Third-party verification
│       ├── Automated verification systems
│       └── Digital verification services
└── Supporting Documentation
    ├── Optional but helpful
    │   ├── Bank statements (showing balances)
    │   ├── Investment statements
    │   ├── Property ownership documents
    │   └── Letter of employment
    └── For specific situations
        ├── Marriage certificate (name changes)
        ├── Divorce decree (alimony/child support)
        ├── Immigration documents (visa, green card)
        └── Court documents (if applicable)
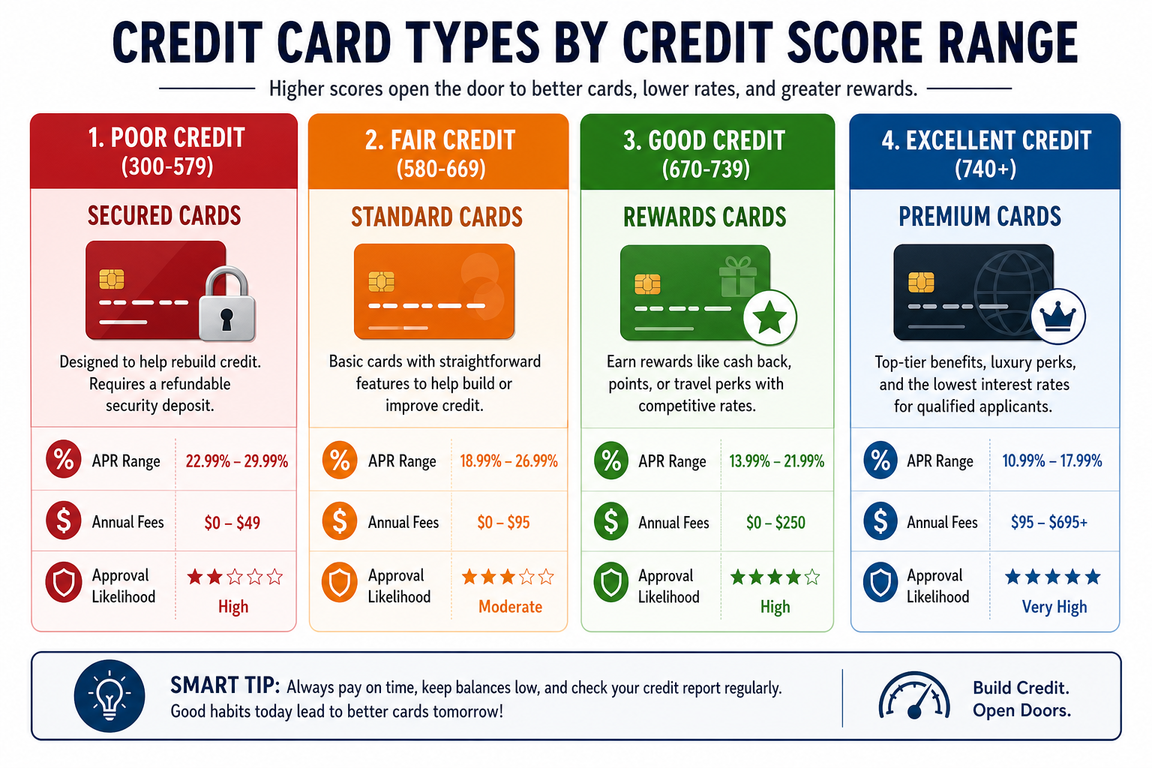
4️⃣ Choose the Right Credit Card for Your Profile
Credit Card Selection Semantic Framework
Selecting the appropriate credit card for your unique financial situation and creditworthiness is absolutely crucial for approval success. Different credit cards are designed for different credit profiles, and applying for a card that matches your credit score range dramatically increases your approval chances.
Credit Card Category Matching:
Credit Card Taxonomy
├── Credit Score Range: Below 620 (Poor Credit)
│   ├── Card Types
│   │   ├── Secured Credit Cards
│   │   │   ├── Requirement: Cash deposit equal to limit
│   │   │   ├── Deposit purpose: Collateral/security
│   │   │   ├── Credit limit: Equal to deposit amount
│   │   │   ├── Approval rate: 90%+
│   │   │   ├── APR range: 20-29%
│   │   │   ├── Annual fee: $0-$75
│   │   │   ├── Graduation timeline: 6-24 months
│   │   │   └── Best for: Building credit from scratch
│   │   ├── Credit-Builder Cards
│   │   │   ├── Target audience: Limited credit history
│   │   │   ├── Approval criteria: Flexible
│   │   │   ├── APR range: 15-25%
│   │   │   ├── Credit limit: $200-$1,000
│   │   │   ├── Annual fee: $0-$25
│   │   │   ├── Features: Basic functionality
│   │   │   └── Best for: New to credit
│   │   └── Specialty Subprime Cards
│   │       ├── Approval likelihood: High
│   │       ├── APR range: 25-35%+
│   │       ├── Annual fees: $50-$250
│   │       ├── Features: Minimal
│   │       ├── Caution: Often predatory
│   │       └── Note: Avoid high-fee options
│   ├── Strategy
│   │   ├── Prioritize secured cards
│   │   ├── Avoid high annual fees
│   │   ├── Focus on building history
│   │   └── Minimize costs
│   └── Timeline
│       └── Graduate to unsecured card after 6-24 months
├── Credit Score Range: 620-669 (Fair Credit)
│   ├── Card Types
│   │   ├── Fair Credit Cards
│   │   │   ├── Approval likelihood: 70-80%
│   │   │   ├── APR range: 15-25%
│   │   │   ├── Annual fees: $0-$75
│   │   │   ├── Rewards: Basic cash back (1-1.5%)
│   │   │   ├── Credit limit: $500-$2,500
│   │   │   └── Best for: Rebuilding credit
│   │   ├── No Annual Fee Cards
│   │   │   ├── Approval likelihood: 75-85%
│   │   │   ├── APR range: 16-24%
│   │   │   ├── Annual fee: $0
│   │   │   ├── Rewards: Minimal
│   │   │   └── Best for: Cost-conscious borrowers
│   │   └── Standard Credit Cards
│   │       ├── Approval likelihood: 70-80%
│   │       ├── APR range: 15-22%
│   │       ├── Annual fees: $0-$50
│   │       ├── Rewards: 1-2% cash back
│   │       └── Best for: Fair credit profile
│   ├── Comparison Focus
│   │   ├── Annual Percentage Rate (APR)
│   │   ├── Annual fees vs. benefits
│   │   ├── Introductory offers
│   │   ├── Grace period length
│   │   └── Rewards structure
│   └── Strategy
│       ├── Minimize annual costs
│       ├── Compare APR offers
│       ├── Focus on rewards matching spending
│       └── Build credit responsibly
├── Credit Score Range: 670-739 (Good Credit)
│   ├── Card Types
│   │   ├── Good Credit Cards
│   │   │   ├── Approval likelihood: 80-90%
│   │   │   ├── APR range: 12-20%
│   │   │   ├── Annual fees: $0-$95
│   │   │   ├── Rewards: 2-3% cash back
│   │   │   ├── Credit limit: $2,500-$7,500
│   │   │   └── Best for: Improving profiles
│   │   ├── Rewards Cards
│   │   │   ├── Approval likelihood: 75-85%
│   │   │   ├── APR range: 12-19%
│   │   │   ├── Annual fees: $0-$95
│   │   │   ├── Rewards: 1.5-5% depending on category
│   │   │   ├── Bonuses: Welcome bonuses available
│   │   │   └── Best for: Active card users
│   │   └── Balance Transfer Cards
│   │       ├── Approval likelihood: 70-80%
│   │       ├── APR range: 0% intro + standard
│   │       ├── Balance transfer fee: 3-5%
│   │       ├── Intro period: 6-12 months
│   │       └── Best for: Debt consolidation
│   ├── Evaluation Criteria
│   │   ├── Rewards matching spending patterns
│   │   ├── Annual fee justification
│   │   ├── Introductory offers
│   │   ├── APR for potential balance carrying
│   │   └── Cardholder benefits
│   └── Strategy
│       ├── Choose rewards matching spending
│       ├── Evaluate annual fee value
│       ├── Compare intro offers
│       └── Focus on APR for borrowing
└── Credit Score Range: 740+ (Excellent Credit)
    ├── Card Types
    │   ├── Premium Rewards Cards
    │   │   ├── Approval likelihood: 90%+
    │   │   ├── APR range: 10-18%
    │   │   ├── Annual fees: $95-$550
    │   │   ├── Rewards: 3-5% base + 5%+ categories
    │   │   ├── Welcome bonus: $500-$2,000+ value
    │   │   ├── Benefits: Lounge access, travel insurance
    │   │   └── Best for: Premium card enthusiasts
    │   ├── Elite Travel Cards
    │   │   ├── Approval likelihood: 85-95%
    │   │   ├── APR range: 10-17%
    │   │   ├── Annual fees: $150-$550
    │   │   ├── Rewards: Miles or points for travel
    │   │   ├── Benefits: Airport lounge, TSA PreCheck
    │   │   ├── Perks: Hotel upgrades, airline credits
    │   │   └── Best for: Frequent travelers
    │   ├── Luxury Cards
    │   │   ├── Approval likelihood: 70-90%
    │   │   ├── APR range: 10-17%
    │   │   ├── Annual fees: $250-$800+
    │   │   ├── Rewards: Premium cash back/points
    │   │   ├── Perks: Concierge, exclusive events
    │   │   ├── Benefits: Platinum tier status
    │   │   └── Best for: Ultra-high spenders
    │   └── Business/Premium Cards
    │       ├── Approval likelihood: 85-95%
    │       ├── APR range: 8-18%
    │       ├── Annual fees: $0-$595
    │       ├── Rewards: Bonus categories for business
    │       ├── Benefits: Purchase protection, insurance
    │       └── Best for: Business spending
    ├── Premium Features Available
    │   ├── Rewards
    │   │   ├── Cash back: 2-5%
    │   │   ├── Points: 1.5-3x per dollar
    │   │   ├── Miles: 2-5 miles per dollar
    │   │   └── Bonuses: $500-$2,000+
    │   ├── Insurance and Protection
    │   │   ├── Purchase protection
    │   │   ├── Extended warranty
    │   │   ├── Travel delay insurance
    │   │   ├── Trip cancellation insurance
    │   │   └── Rental car insurance
    │   ├── Travel Benefits
    │   │   ├── Airport lounge access
    │   │   ├── Global Entry/TSA PreCheck credits
    │   │   ├── Airline fee credits
    │   │   ├── Hotel elite status
    │   │   └── Airport concierge
    │   └── Lifestyle Benefits
    │       ├── Concierge services
    │       ├── Exclusive event access
    │       ├── Restaurant reservations
    │       └── Luxury shopping privileges
    ├── Value Assessment
    │   ├── Annual fee vs. benefits received
    │   ├── Rewards earning vs. actual spending
    │   ├── Insurance/protection utilization
    │   ├── Travel benefit usage
    │   └── Lifestyle perks relevance
    └── Strategy
        ├── Select rewards matching highest spend
        ├── Maximize signup bonuses
        ├── Leverage category bonuses
        ├── Utilize premium benefits
        └── Manage multiple premium cards
5️⃣ Apply Strategically
Strategic Application Semantic Model
Strategic application practices are absolutely essential to maximizing your approval chances while minimizing negative impacts to your credit score. Understanding best practices for credit card applications is crucial.
Application Strategy Framework:
Strategic Credit Card Application
├── Application Method
│   ├── Online Application
│   │   ├── Processing time: Minutes to hours
│   │   ├── Decision timeline: Instant to 2-3 days
│   │   ├── Documentation: Digital upload
│   │   ├── Verification: Real-time validation
│   │   ├── Best for: Standard applications
│   │   ├── Advantages: Speed, convenience
│   │   └── Success rate: Highest
│   ├── Phone Application
│   │   ├── Processing time: 2-5 business days
│   │   ├── Decision timeline: Same day to 1 week
│   │   ├── Verification: Representative assisted
│   │   ├── Best for: Complex situations
│   │   ├── Advantages: Personal assistance
│   │   └── Success rate: Moderate
│   └── In-Person Application
│       ├── Processing time: Same day to 1 week
│       ├── Decision timeline: Same day possible
│       ├── Verification: Document inspection
│       ├── Best for: Special circumstances
│       ├── Advantages: Immediate assistance
│       └── Success rate: Varies
├── Application Frequency
│   ├── Single Application Approach
│   │   ├── Frequency: One application every 3-6 months
│   │   ├── Hard inquiries: Minimal impact
│   │   ├── Success rate: Higher per application
│   │   ├── Advantages: Planned, strategic
│   │   └── Timeline: Longer to build portfolio
│   ├── Multiple Application Approach
│   │   ├── Frequency: 2-3 applications within 45 days
│   │   ├── Hard inquiries: Combined into one inquiry
│   │   ├── Best for: Rate shopping (same product)
│   │   ├── Advantages: Faster approval process
│   │   └── Limitation: Same product type only
│   └── Strategic Spacing
│       ├── Month 1: Application #1
│       ├── Months 2-5: Wait period (rejection recovery)
│       ├── Month 6: Application #2
│       └── Repeat: Every 6 months for optimal spacing
├── Application Timing
│   ├── Credit Score Factors
│   │   ├── Wait period: After high utilization reduction
│   │   ├── Optimal timing: 1-2 months after improvement
│   │   ├── Avoiding timing: Within 30 days of inquiry
│   │   └── Seasonal timing: Less competition in off-season
│   ├── Financial Situation Factors
│   │   ├── Income documentation fresh: Recent pay stub
│   │   ├── Stable employment: 3+ months in position
│   │   ├── Avoid timing: During job transition
│   │   ├── Avoid timing: During major debt payoff
│   │   └── Best timing: After income increase verified
│   ├── Life Event Timing
│   │   ├── After major changes: Wait 3-6 months
│   │   ├── After relocation: Wait 1-2 months
│   │   ├── After marriage: Update documentation
│   │   ├── After job change: Wait for stability
│   │   └── After income increase: Immediate positive
│   └── Seasonal Timing
│       ├── Holiday season: Higher approval rates
│       ├── New year: Banks offer promotions
│       ├── Summer months: Stable employment period
│       └── Tax time: Income documentation available
└── Application Optimization
    ├── Information Accuracy
    │   ├── Legal name: Exact match to ID
    │   ├── Address: Current residential
    │   ├── Employment: Verified information
    │   ├── Income: Conservative, documented amount
    │   └── Assets: Truthful disclosure
    ├── Supporting Documentation
    │   ├── Attached at application: Speeds processing
    │   ├── High-quality scans: Clear, legible
    │   ├── Complete documents: Both sides if needed
    │   ├── Recent dates: Current information
    │   └── Multiple sources: Stronger application
    ├── Application Presentation
    │   ├── Professional appearance: Organized information
    │   ├── Clear writing: Legible, correct spelling
    │   ├── Complete sections: No blank fields
    │   ├── Consistent information: Matching across form
    │   └── Explanation notes: Context for issues
    └── Follow-up Strategy
        ├── Monitor email: Check for requests
        ├── Respond quickly: Pending documentation
        ├── Call reconsideration line: If denied
        ├── Ask about upgrades: After 6 months approval
        └── Request limit increases: After 12 months
6️⃣ Understand the Application Process in 2026
Modern Credit Card Application Semantic Framework
The credit card application process in 2026 has evolved significantly with advances in financial technology and digital verification systems. Understanding how modern credit card applications work will help you navigate the process with confidence.
Application Process Technology Stack:
2026 Credit Card Application Technology
├── Digital Application Platform
│   ├── Components
│   │   ├── Web interface (desktop, mobile)
│   │   ├── Information collection system
│   │   ├── Document upload functionality
│   │   ├── Real-time validation
│   │   ├── Automated decision engine
│   │   └── Conditional approval workflow
│   ├── Security Features
│   │   ├── SSL/TLS encryption
│   │   ├── Two-factor authentication
│   │   ├── Fraud detection systems
│   │   ├── PCI DSS compliance
│   │   └── Data protection protocols
│   └── User Experience
│       ├── Mobile-optimized forms
│       ├── Auto-fill capabilities
│       ├── Progress indicators
│       ├── Real-time field validation
│       └── Instant decision notification
├── Artificial Intelligence/Machine Learning Systems
│   ├── Decision Engine
│   │   ├── Credit score analysis
│   │   ├── Income verification
│   │   ├── Debt assessment
│   │   ├── Risk modeling
│   │   └── Pattern recognition
│   ├── Data Evaluation
│   │   ├── Traditional credit bureau data
│   │   ├── Alternative credit data
│   │   ├── Bank transaction analysis
│   │   ├── Employment verification
│   │   └── Behavioral patterns
│   ├── Decision Outcomes
│   │   ├── Instant approval (70% of applications)
│   │   ├── Conditional approval (20% of applications)
│   │   ├── Pending review (5% of applications)
│   │   └── Denial (5% of applications)
│   └── Algorithm Benefits
│       ├── Speed (minutes vs. days)
│       ├── Consistency (same criteria applied)
│       ├── Inclusivity (considers alternative data)
│       ├── Accuracy (learns from outcomes)
│       └── Bias reduction (when properly designed)
├── Real-Time Verification Systems
│   ├── Identity Verification
│   │   ├── ID validation (optical scanning)
│   │   ├── Facial recognition (biometric)
│   │   ├── Document authentication (anti-fraud)
│   │   └── Database cross-reference
│   ├── Employment Verification
│   │   ├── Work Number system (automated)
│   │   ├── Direct employer contacts
│   │   ├── Employment databases
│   │   └── Document-based verification
│   ├── Income Verification
│   │   ├── Pay stub processing (OCR technology)
│   │   ├── Tax return analysis
│   │   ├── Bank deposit verification
│   │   ├── Open banking connections
│   │   └── Real-time income confirmation
│   └── Address Verification
│       ├── USPS database lookup
│       ├── Utility company databases
│       ├── Postal service verification
│       └── Google Maps validation
├── Credit Bureau Integration
│   ├── Real-Time Pull Capability
│   │   ├── Equifax integration
│   │   ├── Experian integration
│   │   ├── TransUnion integration
│   │   └── Multiple score retrieval
│   ├── Credit Report Access
│   │   ├── Full report data
│   │   ├── Account history
│   │   ├── Inquiry history
│   │   └── Public records
│   └── Decision Impact
│       ├── Score-based decisions (primary)
│       ├── Report-based analysis (secondary)
│       ├── Trend identification
│       └── Risk assessment
└── Alternative Credit Data Sources
    ├── Credit bureaus
    │   ├── Clarity (banking)
    │   ├── eScore (alternative)
    │   └── Others (emerging)
    ├── Open Banking Connections
    │   ├── Bank account access (with permission)
    │   ├── Transaction history analysis
    │   ├── Spending pattern evaluation
    │   └── Account balance verification
    ├── Utility Payment Reports
    │   ├── Experian Boost (utility integration)
    │   ├── Electric bill history
    │   ├── Gas bill history
    │   ├── Water bill history
    │   └── Payment timeliness
    ├── Rental Payment History
    │   ├── Rent Bureau (rental payments)
    │   ├── LevelCredit (rent reporting)
    │   ├── Landlord verification
    │   └── On-time payment history
    └── Emerging Data Sources
        ├── Cell phone payment history
        ├── Insurance premium payments
        ├── Telecom payment records
        ├── Subscription service payments
        └── Alternative income sources
7️⃣ If You’re Denied
Denial Recovery Semantic Framework
Receiving a credit card denial is disappointing, but it’s not the end of your credit journey. Denials are often temporary setbacks that you can overcome by addressing the specific reasons for the denial.
Denial Management Strategy:
Credit Card Denial Recovery Process
├── Immediate Actions (Within 24-48 hours)
│   ├── Request Denial Reason
│   │   ├── Required by law: FCRA compliance
│   │   ├── Obtain from: Issuer notice or call
│   │   ├── Specific reason needed: Not just "denied"
│   │   ├── Documentation: Keep for records
│   │   ├── Examples of reasons
│   │   │   ├── "Credit score too low"
│   │   │   ├── "Insufficient income"
│   │   │   ├── "High debt-to-income ratio"
│   │   │   ├── "Recent late payments"
│   │   │   ├── "Too many inquiries"
│   │   │   ├── "Insufficient credit history"
│   │   │   └── "Account with us"
│   │   └── Understanding reasons: Guides improvement
│   └── Request Reconsideration
│       ├── Timing: Call within 24 hours
│       ├── Who to call: Reconsideration department
│       ├── What to ask: "Can you reconsider?"
│       ├── What to provide: Additional information
│       ├── Success rate: 10-30% of cases
│       ├── Additional information
│       │   ├── Promotion/new income
│       │   ├── Explanation of late payment
│       │   ├── Recent improvement
│       │   └── Co-signer availability
│       └── Outcome possibilities
│           ├── Approved with conditions
│           ├── Approved with lower limit
│           ├── Reconsideration pending
│           └── Denial upheld
├── Analysis Phase (Days 2-7)
│   ├── Review Denial Reason
│   │   ├── Read written denial notice
│   │   ├── Compare to self-assessment
│   │   ├── Identify specific factors
│   │   ├── Determine if valid
│   │   └── Plan improvements
│   ├── Check Credit Report
│   │   ├── Obtain free credit reports
│   │   ├── Review for errors
│   │   ├── Identify recent negative items
│   │   ├── Assess overall profile
│   │   └── Look for improvement opportunities
│   ├── Calculate DTI Ratio
│   │   ├── Sum all monthly debts
│   │   ├── Divide by monthly income
│   │   ├── Identify if too high
│   │   ├── Find debt reduction opportunities
│   │   └── Calculate new DTI scenarios
│   └── Assess Income Documentation
│       ├── Review what was provided
│       ├── Ensure recency (within 60 days)
│       ├── Check accuracy of amounts
│       ├── Identify missing documentation
│       └── Gather additional documents
├── Improvement Phase (Weeks 2-12)
│   ├── Address Credit Score Issues
│   │   ├── Pay down revolving balances
│   │   ├── Dispute errors on report
│   │   ├── Become authorized user
│   │   ├── Make all payments on time
│   │   ├── Target improvement: 50-100 points
│   │   ├── Timeline: 6-8 weeks for improvement
│   │   └── Patience with credit reporting
│   ├── Reduce Debt-to-Income Ratio
│   │   ├── Pay down existing debts
│   │   ├── Focus on highest utilization cards
│   │   ├── Consider debt consolidation
│   │   ├── Increase income if possible
│   │   ├── Target ratio: Below 36%
│   │   ├── Timeline: 2-6 months
│   │   └── Document improvements
│   ├── Address Late Payments
│   │   ├── Make all future payments on time
│   │   ├── Set up automatic payments
│   │   ├── Explain previous issues if temporary
│   │   ├── Show recent positive history
│   │   ├── Timeline: 6-12 months
│   │   └── Impact: Decreases over time
│   ├── Improve Income Documentation
│   │   ├── Secure recent pay stubs
│   │   ├── Get employment letter
│   │   ├── Gather past 2 years W-2s or taxes
│   │   ├── Document additional income
│   │   └── Prepare supporting documents
│   └── Build Additional Credit
│       ├── Get secured credit card
│       ├── Become authorized user
│       ├── Obtain credit-builder loan
│       ├── Establish positive history
│       └── Timeline: 6+ months
├── Reapplication Phase (Month 3+)
│   ├── Same Issuer Reapplication
│   │   ├── Timing: 30-90 days after denial
│   │   ├── Condition: Improvements made
│   │   ├── Updated information: Provide new docs
│   │   ├── Reconsideration consideration: Mention
│   │   ├── Same credit: All products
│   │   ├── Different credit: Alternative card
│   │   └── Success rate: 30-40% with improvements
│   ├── Different Issuer Application
│   │   ├── Timing: Can apply sooner
│   │   ├── Strategy: Choose different card type
│   │   ├── Research: Issuer approval rates
│   │   ├── Match: Card to credit profile
│   │   ├── Application spacing: Every 2-3 months
│   │   └── Success rate: Higher with different issuer
│   └── Strategic Card Selection
│       ├── Niche lenders: Specialize in credit type
│       ├── Credit-builder cards: Easier approval
│       ├── Secured cards: Guaranteed approval
│       ├── Online banks: More flexible criteria
│       └── Credit unions: Member advantages
└── Long-Term Strategy (Months 4-12)
    ├── Continued Improvement Focus
    │   ├── Build credit history
    │   ├── Increase credit score
    │   ├── Reduce debt levels
    │   ├── Establish emergency fund
    │   └── Improve overall financial health
    ├── Monitoring and Documentation
    │   ├── Track credit score progression
    │   ├── Monitor credit report changes
    │   ├── Document income changes
    │   ├── Keep debt paydown records
    │   └── Maintain financial documents
    ├── Multiple Approval Pathways
    │   ├── Alternative credit card secured
    │   ├── Authorization user status
    │   ├── Credit-builder loan obtained
    │   ├── Traditional card application prepared
    │   └── Combination approach
    └── Lesson Integration
        ├── Understand denial triggers
        ├── Prevent future denials
        ├── Plan applications strategically
        ├── Build financial resilience
        └── Develop long-term credit strategy
8️⃣ After Approval: Building Your Credit
Post-Approval Semantic Framework
Getting approved for your credit card is a wonderful achievement, but it’s actually the beginning of your credit-building journey rather than the end. How you use your card after approval significantly impacts your credit score and determines whether you’ve made a smart financial decision or will end up in debt.
Credit Card Usage Strategy:
Post-Approval Credit Building
├── Initial Card Setup (Days 1-7)
│   ├── Card Activation
│   │   ├── Activate via website or phone
│   │   ├── Confirm receipt of card
│   │   ├── Verify card details
│   │   ├── Set up online account access
│   │   └── Download mobile app
│   ├── Security Setup
│   │   ├── Change PIN (if applicable)
│   │   ├── Set fraud alerts
│   │   ├── Confirm contact information
│   │   ├── Review fraud protections
│   │   └── Understand dispute process
│   └── Initial Review
│       ├── Review terms and conditions
│       ├── Note APR and terms
│       ├── Identify rewards structure
│       ├── Understand annual fee
│       └── Review grace period
├── Credit Building Usage (Months 1-6)
│   ├── Transaction Strategy
│   │   ├── Make small purchases monthly
│   │   ├── Purchase items you'd buy anyway
│   │   ├── Keep balance low (5-10% of limit)
│   │   ├── Make diverse transactions
│   │   ├── Show activity to issuer
│   │   ├── Examples of purchases
│   │   │   ├── Groceries ($50 monthly)
│   │   │   ├── Gas ($40 monthly)
│   │   │   ├── Utilities ($30 monthly if possible)
│   │   │   ├── Streaming services ($15 monthly)
│   │   │   └── One larger purchase ($150-200)
│   │   └── Total monthly spend: $200-300
│   ├── Payment Strategy
│   │   ├── Set up automatic payments
│   │   ├── Pay full balance monthly
│   │   ├── Never carry interest charges
│   │   ├── Make payments early (before due date)
│   │   ├── Consider paying before statement closing
│   │   ├── Benefits of full payment
│   │   │   ├── Zero interest charges
│   │   │   ├── Build perfect payment history
│   │   │   ├── Lower reported utilization
│   │   │   ├── Demonstrate responsibility
│   │   │   └── Build lender relationship
│   │   └── Payment timing
│   │       ├── Statement closing date: 1st of month
│   │       ├── Due date: 25th of month
│   │       ├── Pay-before-closing date: 28th previous month
│   │       └── Gap: 3-week buffer for processing
│   ├── Utilization Management
│   │   ├── Monitor reported balance
│   │   ├── Keep utilization under 10%
│   │   ├── Example calculation
│   │   │   ├── Credit limit: $1,000
│   │   │   ├── Maximum balance: $100
│   │   │   ├── Reported utilization: 10%
│   │   │   ├── Impact on score: Positive
│   │   │   └── Growth potential: High
│   │   └── Optimization strategy
│   │       ├── Pay down before statement closing
│   │       ├── Request limit increase early
│   │       ├── Increase available credit
│   │       └── Further lower utilization
│   └── Activity Frequency
│       ├── Monthly usage: Essential
│       ├── Inactivity risk: Account closure
│       ├── Show responsiveness to issuer
│       ├── Build transaction history
│       └── Timeline: 6 months of activity
├── Credit Building Optimization (Months 6-12)
│   ├── Request Credit Limit Increase
│   │   ├── Timing: After 6 months on-time payments
│   │   ├── Method: Request via phone, app, or website
│   │   ├── Inquiry type: Soft or hard (ask which)
│   │   ├── Typical increase: 25-100% of original
│   │   ├── Benefits of increase
│   │   │   ├── Higher available credit
│   │   │   ├── Lower utilization ratio
│   │   │   ├── Improved credit score
│   │   │   ├── Greater spending flexibility
│   │   │   └── Shows issuer confidence
│   │   ├── Qualification factors
│   │   │   ├── Payment history: Perfect
│   │   │   ├── Account age: 6+ months
│   │   │   ├── Income increase: If available
│   │   │   ├── Credit score improvement: Evident
│   │   │   └── Usage history: Good
│   │   └── Success rate: 60-80% of requests
│   ├── Automatic Limit Increases
│   │   ├── Issuer review: Periodic (quarterly/biannual)
│   │   ├── Soft inquiry: No impact on score
│   │   ├── Qualification: Responsible usage
│   │   ├── Timing: Usually unexpected
│   │   ├── Notification: Email or statement
│   │   └── Acceptance: Automatic in most cases
│   ├── Building Resilience
│   │   ├── Emergency fund progress
│   │   ├── Savings accumulation
│   │   ├── Debt reduction on other accounts
│   │   ├── Income stability
│   │   └── Financial goal progress
│   └── Score Improvement Tracking
│       ├── Check score monthly
│       ├── Use free monitoring services
│       ├── Track improvements
│       ├── Expected score increase: 50-100 points
│       └── Timeline: 6-12 months for significant change
├── Long-Term Card Management (Year 2+)
│   ├── Graduated Usage
│   │   ├── Maintain active usage: Monthly
│   │   ├── Possibly increase spending
│   │   ├── Continue full-balance payment
│   │   ├── Monitor all accounts
│   │   └── Manage multiple cards (if applicable)
│   ├── Account Retention
│   │   ├── Keep account open indefinitely
│   │   ├── Never close even if unused
│   │   ├── Keep active with occasional use
│   │   ├── Use as backup payment method
│   │   ├── Maintain payment compliance
│   │   └── Build account history length
│   ├── Portfolio Building
│   │   ├── Apply for additional cards (as appropriate)
│   │   ├── Space applications 3-6 months apart
│   │   ├── Diversify card types
│   │   ├── Build rewards portfolio
│   │   └── Increase credit limits overall
│   └── Financial Goal Achievement
│       ├── Improved credit score (740+)
│       ├── Access to premium cards
│       ├── Better interest rates on loans
│       ├── Higher credit limits available
│       ├── Financial flexibility increased
│       └── Long-term wealth building
└── Usage Mistakes to Avoid
    ├── Carrying monthly balance
    │   ├── Unnecessary interest charges
    │   ├── Reduced score impact
    │   ├── Negates credit-building benefits
    │   └── Wastes money on interest
    ├── High utilization
    │   ├── Reports high utilization to bureaus
    │   ├── Negatively impacts credit score
    │   ├── Signals financial stress to lenders
    │   └── Limits future credit approval
    ├── Missed payments
    │   ├── Immediate account damage
    │   ├── 50-100+ point score reduction
    │   ├── 7-year reporting period
    │   ├── Late fees and higher APR
    │   └── Approval denials for other credit
    ├── Account closure
    │   ├── Reduces available credit
    │   ├── Increases utilization ratio
    │   ├── Removes account history
    │   ├── Potentially closes account
    │   └── Damages credit score
    ├── Multiple simultaneous applications
    │   ├── Multiple hard inquiries
    │   ├── Score reduction compounded
    │   ├── Increased risk perception
    │   ├── Lower approval odds
    │   └── Avoid despite temptation
    └── Fraud complacency
        ├── Not monitoring statements
        ├── Missing fraudulent charges
        ├── Delaying fraud reporting
        ├── Losing consumer protections
        └── Financial damage potential
📊 Key Factors for Credit Card Approval in 2026
Approval Factor Semantic Analysis
Understanding the relative importance of different factors in credit card approval decisions helps you prioritize where to focus your efforts when preparing your application.
Approval Factor Weighting Model:
Credit Card Approval Factor Analysis

FACTOR 1: Credit Score (35% Impact Weight)
├── Definition
│   └── Numerical rating of creditworthiness (300-850)
├── Components of Credit Score
│   ├── Payment history: 35% of score
│   ├── Amounts owed: 30% of score
│   ├── Length of history: 15% of score
│   ├── New credit: 10% of score
│   └── Credit mix: 10% of score
├── Score Ranges and Interpretation
│   ├── 300-579 (Poor): Limited options
│   ├── 580-669 (Fair): Some options
│   ├── 670-739 (Good): Most options
│   ├── 740-799 (Very Good): Best options
│   └── 800-850 (Excellent): Premium only
├── Score Impact on Approval
│   ├── Below 620: Secured/builder cards
│   ├── 620-669: Fair credit cards
│   ├── 670-739: Good credit cards
│   ├── 740+: Premium cards available
│   └── 800+: Elite card tier access
├── Your Action
│   ├── Immediate: Check current score
│   ├── Month 1: Begin improvement plan
│   ├── Timeline: Target 700+ before applying
│   ├── Ideal: Achieve 760+ for best terms
│   └── Stretch: Pursue 800+ for premium access
├── Expected Improvement
│   ├── Timeline: 3-6 months for 50-100 point increase
│   ├── With aggressive effort: 100-150 points in 3 months
│   ├── Sustained effort: 200+ points in 6-12 months
│   ├── Perfect plan: 300+ points in 12-24 months
│   └── Note: Results vary by starting point

FACTOR 2: Income Verification (30% Impact Weight)
├── Definition
│   └── Documented proof of stable income
├── Income Types Evaluated
│   ├── W-2 employment (most stable)
│   ├── Self-employment (requires documentation)
│   ├── Commission/bonus (variable accepted)
│   ├── Rental income (with lease)
│   ├── Investment income (with statements)
│   ├── Social Security/pension (with statements)
│   └── Other sources (documentation dependent)
├── Verification Methods
│   ├── Pay stub verification (30-60 days old)
│   ├── W-2 forms (past 2 years)
│   ├── Tax returns (past 2 years)
│   ├── Offer letter (new employment)
│   ├── Employment verification service
│   ├── Direct employer contact
│   └── Open banking verification (real-time)
├── Income Requirements
│   ├── Minimum monthly: $1,250-$2,000
│   ├── Minimum annual: $15,000-$24,000
│   ├── For higher limits: $30,000+ annually
│   ├── For premium cards: $50,000+ annually
│   └── Note: Varies by issuer
├── Your Action
│   ├── Immediate: Document all income
│   ├── Gather: Recent pay stubs or tax returns
│   ├── Ensure: Income documentation within 60 days
│   ├── Verify: Accuracy of reported income
│   └── Apply: Once documentation in order
├── Expected Outcome
│   ├── Verified income: Higher approval odds
│   ├── Stable history: 2+ years preferred
│   ├── Growth trajectory: Positive trend helpful
│   ├── Multiple sources: Strengthens application
│   └── Conservative reporting: Prevents issues

FACTOR 3: Debt-to-Income Ratio (20% Impact Weight)
├── Definition
│   └── Percentage of income committed to debt
├── Calculation
│   ├── Total monthly debt ÷ gross monthly income
│   ├── Example: $1,500 debt ÷ $5,000 income = 30%
│   ├── Includes: Credit cards, loans, rent/mortgage
│   ├── Excludes: Utilities, groceries, insurance
│   └── Updating: Recalculate monthly
├── Lender Preferences
│   ├── Excellent: Below 20%
│   ├── Good: 20-36%
│   ├── Acceptable: 36-43%
│   ├── Risky: 43%+
│   └── Automatic denial: 50%+
├── Impact on Credit Card
│   ├── Below 28%: Favorable
│   ├── 28-36%: Standard range
│   ├── 36-43%: May need review
│   ├── Above 43%: High rejection rate
│   └── Strategy: Keep below 36%
├── Your Action
│   ├── Calculate: Current DTI ratio
│   ├── Identify: High-impact debts
│   ├── Pay down: $500-1,000 per month
│   ├── Target: Get below 36% before applying
│   └── Timeline: 2-6 months for improvement
├── Expected Outcome
│   ├── Better ratio: Improved approval odds
│   ├── Lower payments: More payment flexibility
│   ├── Higher limit: Increased credit access
│   ├── Better APR: More favorable terms
│   └── Multiple approvals: Expanded portfolio

FACTOR 4: Credit History Length (10% Impact Weight)
├── Definition
│   └── Age and duration of credit accounts
├── Components
│   ├── Age of oldest account (most important)
│   ├── Age of newest account (least important)
│   ├── Average age of all accounts
│   ├── Account history timeline
│   └── Continuous account usage
├── Impact on Score
│   ├── 0-1 year: Building stage
│   ├── 1-3 years: Establishing stage
│   ├── 3-7 years: Growing stage
│   ├── 7+ years: Mature stage
│   └── 10+ years: Excellent stage
├── Lender Preferences
│   ├── Short history: Limited options
│   ├── Moderate history: More options
│   ├── Long history: Best options
│   ├── Account diversity: Helpful
│   └── Continuous activity: Important
├── Your Action
│   ├── Keep: All old accounts open
│   ├── Never close: Even unused cards
│   ├── Use occasionally: To keep active
│   ├── Monitor: For activity/closure
│   └── Timeline: Longer is better
├── Expected Outcome
│   ├── Older accounts: Better creditworthiness
│   ├── Multiple accounts: Improved rating
│   ├── Continuous history: Trust-building
│   ├── Length advantage: Grows monthly
│   └── Combined with others: Strongest factor

FACTOR 5: Credit Mix (5% Impact Weight)
├── Definition
│   └── Variety of credit types managed
├── Types of Credit
│   ├── Revolving credit (credit cards)
│   ├── Installment loans (personal loans)
│   ├── Mortgage (home loan)
│   ├── Auto loans
│   ├── Student loans
│   └── Other credit types
├── Lender Preferences
│   ├── Multiple types: Slightly positive
│   ├── At least 2-3 types: Beneficial
│   ├── Good management: Critical
│   ├── Variety: Nice to have
│   └── Not essential: Can have only credit cards
├── Impact on Score
│   ├── Limited mix: Slight negative
│   ├── No mix: 5-10 point impact
│   ├── Balanced mix: 5-10 point positive
│   ├── Excellent mix: Maximized score
│   └── With good management: Critical factor
├── Your Action
│   ├── Don't force: Opening unwanted accounts
│   ├── Maintain: Existing varied accounts
│   ├── Build naturally: As needs arise
│   ├── Prioritize: Other factors (score, DTI)
│   └── Accept: If not limiting
├── Expected Outcome
│   ├── Natural diversification: Helpful
│   ├── Combined with others: Strengthens profile
│   ├── Responsible management: Most important
│   ├── Time-based development: Organic growth
│   └── Not primary focus: Focus on score/DTI
⚠️ Common Approval Mistakes to Avoid
Mistake Prevention Semantic Framework
Avoiding these common mistakes will significantly improve your approval chances and protect your credit health throughout the process.
Common Mistake Analysis:
Credit Card Application Mistakes

MISTAKE 1: Multiple Simultaneous Applications
├── What It Is
│   └── Submitting 2+ applications within 30 days
├── Why It's Damaging
│   ├── Multiple hard inquiries
│   │   ├── Each reduces score 5-10 points
│   │   ├── Combined: 15-50 point reduction
│   │   ├── Visible to other lenders
│   │   └── Compounded impact
│   ├── Risk signal
│   │   ├── Desperate for credit
│   │   ├── Repeated rejections possible
│   │   ├── Financial stress indicators
│   │   └── Higher perceived risk
│   └── Approval impact
│       ├── Lower approval odds
│       ├── Lower credit limits offered
│       ├── Higher APRs assigned
│       └── Conditions/requirements added
├── Score Impact
│   ├── Temporary: 1-3 months impact
│   ├── Magnitude: 15-50 points total
│   ├── Recovery: Score rebounds after 3 months
│   ├── Permanent: None (temporary only)
│   └── Timeline: Impacts fade in 6-12 months
├── How to Avoid It
│   ├── Apply once: Every 3-6 months
│   ├── Wait for decision: Before applying elsewhere
│   ├── Space applications: 6 months ideal
│   ├── Strategic timing: Plan applications carefully
│   └── One card at a time: Build patiently
├── Recovery Strategy
│   ├── Stop applying: Let inquiries age
│   ├── Improve score: Work on other factors
│   ├── Time passage: Most effective (6 months)
│   ├── Continued on-time payments: Help
│   └── No new credit: Avoid further inquiries

MISTAKE 2: Closing Old Credit Cards
├── What It Is
│   └── Closing accounts after paying off or obtaining new card
├── Why It's Damaging
│   ├── Reduces available credit
│   │   ├── Utilization ratio increases
│   │   ├── Higher percentage reported
│   │   ├── Score decrease: 10-50+ points
│   │   └── Approval odds decline
│   ├── Shortens account history
│   │   ├── Average age decreases
│   │   ├── History length reduced
│   │   ├── Scoring impact: 5-15 points
│   │   └── Long-term damage
│   ├── Reduces credit mix
│   │   ├── Fewer account types
│   │   ├── Minor impact: 5 points
│   │   ├── Recommendation: Keep accounts
│   │   └── Avoid closure decisions
│   └── Damages credit score
│       ├── Immediate impact: 10-50+ points
│       ├── Long-term impact: Ongoing
│       ├── Duration: 10+ years (account removal)
│       └── Reversal: Impossible (permanent)
├── Example Impact
│   ├── Before closure
│   │   ├── Available credit: $10,000
│   │   ├── Used credit: $2,000 (20%)
│   │   └── Score: 750
│   ├── After closure (closed $3,000 card)
│   │   ├── Available credit: $7,000
│   │   ├── Used credit: $2,000 (29%)
│   │   ├── Score impact: -10 to -30 points
│   │   └── New score: 720-740
│   └── Result: Score reduction from single closure
├── How to Avoid It
│   ├── Never close accounts: Unless critical reason
│   ├── Keep all cards open: Even if unused
│   ├── Use occasionally: Keep account active
│   ├── Accept small fees: Better than closing
│   └── Maintain zero balance: If no annual fee
├── Exception Scenarios
│   ├── High annual fee: Can outweigh benefits
│   ├── Predatory terms: If clearly harmful
│   ├── Fraud account: Compromised security
│   ├── Excellent score: Can afford small hit
│   └── Last resort: Only when necessary
└── Recovery Strategy
    ├── Don't close more accounts
    ├── Build credit aggressively: Other factors
    ├── Time passage: 3-7 years for healing
    ├── Reopen accounts: If possible
    └── Focus: Future financial health

MISTAKE 3: Major Purchases Before Applying
├── What It Is
│   └── Making large purchases before applying for credit
├── Why It's Damaging
│   ├── Increases utilization ratio
│   │   ├── Higher balance reported
│   │   ├── Higher utilization percentage
│   │   ├── Score reduction: 10-50+ points
│   │   └── Approval odds decline significantly
│   ├── Signals financial stress
│   │   ├── Large spending = financial need
│   │   ├── Lenders perceive distress
│   │   ├── Risk level increases
│   │   └── Approval odds lower
│   ├── DTI ratio worsens
│   │   ├── If financed: New monthly payment
│   │   ├── DTI calculation: Increases
│   │   ├── Approval threshold: May exceed limit
│   │   └── Denial likelihood: Increases
│   └── Timing considerations
│       ├── Within 30 days: Major impact
│       ├── Within 60 days: Some impact
│       ├── After 60 days: Minimal impact
│       └── Within 90 days: Report updated
├── Example Impact
│   ├── Before purchase
│   │   ├── Balance: $1,000
│   │   ├── Limit: $5,000
│   │   ├── Utilization: 20%
│   │   └── Score: 700
│   ├── After $2,000 purchase
│   │   ├── Balance: $3,000
│   │   ├── Limit: $5,000
│   │   ├── Utilization: 60%
│   │   ├── Score impact: -20 to -50 points
│   │   └── New score: 650-680
│   └── Result: Significant score damage
├── How to Avoid It
│   ├── Plan major purchases: After approval
│   ├── Wait for approval: Use new card limit
│   ├── Delay purchases: 30-60 days if possible
│   ├── Save for purchases: Use cash/savings
│   └── Apply first: Then make large purchases
├── Timeline Considerations
│   ├── 3 months before applying: Purchase safely
│   ├── 1 month before: Risky (balance reports)
│   ├── 2 weeks before: Very risky
│   ├── At application: Avoid completely
│   └── After approval: Optimal timing
└── Recovery Strategy
    ├── Wait 30-90 days: For report update
    ├── Pay down balance: Reduce utilization
    ├── Improve score: Through other means
    ├── Time passage: 3-6 months for recovery
    └── Reapply: Once balance reduced

MISTAKE 4: Providing False Information
├── What It Is
│   └── Lying about income, employment, residence, etc.
├── Why It's Damaging
│   ├── Immediate detection
│   │   ├── Modern verification systems
│   │   ├── Employment verification databases
│   │   ├── Income verification services
│   │   ├── Address verification systems
│   │   └── Credit bureau cross-reference
│   ├── Automatic application denial
│   │   ├── Fraud flagged immediately
│   │   ├── Application rejected
│   │   ├── Hard inquiry on credit
│   │   └── Score reduction from inquiry
│   ├── Industry blacklisting
│   │   ├── Marked as fraudulent applicant
│   │   ├── Shared across credit industry
│   │   ├── Future applications declined
│   │   ├── Difficult to obtain credit
│   │   └── Reputation damage
│   ├── Legal consequences
│   │   ├── Credit fraud is federal crime
│   │   ├── Criminal charges possible
│   │   ├── Fines up to $10,000+
│   │   ├── Imprisonment possible
│   │   └── Civil liability exposure
│   └── Account closure risk
│       ├── Approved account may be closed
│       ├── Balance demanded immediately
│       ├── Legal action pursued
│       ├── Credit score destroyed
│       └── References provided to law enforcement
├── Legal Implications
│   ├── Federal law violation: Yes
│   ├── Fraud statute: 15 U.S.C. § 1681k
│   ├── Penalties: Up to 2 years imprisonment
│   ├── Fines: Up to $5,000
│   ├── Restitution: Full fraud amount
│   └── Civil liability: Additional damages
├── Detection Methods
│   ├── Income verification: W-2, tax returns
│   ├── Employment verification: Direct contact
│   ├── Address verification: USPS, utility databases
│   ├── Identity verification: ID authentication
│   ├── Cross-reference checks: Bureau data
│   └── Fraud pattern analysis: AI systems
├── How to Avoid It
│   ├── Always tell truth: On all applications
│   ├── Honest assessment: Of your situation
│   ├── Conservative numbers: Rather than inflated
│   ├── Complete documentation: Truthfully
│   ├── Accept results: Based on real situation
│   └── Address: Instead of fabricating
├── What to Do if Denied
│   ├── Accept decision: Gracefully
│   ├── Don't contest falsely: Won't help
│   ├── Work on improvement: Legitimate approach
│   ├── Reapply later: When ready truthfully
│   ├── Build credit: Through honest means
│   └── Learn from process: For future success
└── Recovery (If Caught)
    ├── Consult attorney: If facing charges
    ├── Cooperate: With investigation
    ├── No reapplication: To same issuer
    ├── Credit damage: 7+ years
    ├── Industry blacklist: For extended period
    └── Focus: On rebuilding legitimately

MISTAKE 5: Ignoring Credit Report Errors
├── What It Is
│   └── Not reviewing credit report for inaccuracies
├── Why It's Damaging
│   ├── Undetected errors compound
│   │   ├── Negative items remain on report
│   │   ├── Score damage continues
│   │   ├── Approval odds reduced
│   │   ├── Terms worsened
│   │   └── Lost opportunities
│   ├── Possible false accounts
│   │   ├── Identity theft signs
│   │   ├── Fraudulent accounts
│   │   ├── Unauthorized inquiries
│   │   ├── Score damage: 50-200+ points
│   │   └── Account damage: Major
│   ├── Incorrect payment history
│   │   ├── Marked as late incorrectly
│   │   ├── Score reduction: 20-100+ points
│   │   ├── Appears to lenders
│   │   ├── Approval impact: Significant
│   │   └── Fixable with dispute
│   ├── Duplicate accounts
│   │   ├── Same account listed twice
│   │   ├── Score appears worse
│   │   ├── Utilization inflated
│   │   ├── History confused
│   │   └── Easily correctable
│   └── Outdated negative items
│       ├── Should have aged off
│       ├── Still reporting on credit
│       ├── Hurting score unnecessarily
│       ├── Fixable through dispute
│       └── 7-10 year statute applies
├── Error Types and Frequency
│   ├── Payment errors: 3-5% of reports
│   ├── Account status errors: 5-8% of reports
│   ├── Duplicate accounts: 2-3% of reports
│   ├── Identity theft: 0.5-1% of reports
│   ├── Personal info errors: 5-10% of reports
│   └── Overall: 20-40% have some error
├── Impact on Score
│   ├── Inaccurate late payment: -50 to -100 points
│   ├── False account: -50 to -200 points
│   ├── Duplicate account: -10 to -50 points
│   ├── Account status error: -20 to -80 points
│   └── Combined errors: -100 to -500+ points
├── How to Avoid It
│   ├── Check reports: Immediately
│   ├── Review annually: At minimum
│   ├── Check before applying: Critical
│   ├── Report fraud: If suspected
│   ├── Dispute errors: Immediately
│   └── Monitor ongoing: Use service
├── Dispute Process
│   ├── Identify error: Document specifically
│   ├── Contact bureau: In writing
│   ├── Provide documentation: Supporting evidence
│   ├── Wait 30 days: Bureau investigation
│   ├── Get results: Written response
│   ├── Follow up: If not resolved
│   └── Timeline: 1-2 months typical
└── Recovery Strategy
    ├── Dispute immediately: As you find errors
    ├── Document all: With evidence
    ├── Follow up: If not responded
    ├── Score improvement: After removal
    ├── Timeline: 2-4 weeks for update
    └── Reapply: Once errors corrected

MISTAKE 6: Applying Without Meeting Requirements
├── What It Is
│   └── Applying for cards you don't qualify for
├── Why It's Damaging
│   ├── Wasted application opportunity
│   │   ├── Hard inquiry on credit
│   │   ├── Score reduction: 5-10 points
│   │   ├── No potential approval
│   │   ├── Likely denial
│   │   └── Should have avoided
│   ├── Automatic denial signals
│   │   ├── Lenders see previous denials
│   │   ├── Risk perception increases
│   │   ├── Future approvals harder
│   │   ├── Confidence in applications lower
│   │   └── Approval odds decline
│   ├── Credit portfolio damage
│   │   ├── More rejections on record
│   │   ├── Credit history reflects rejections
│   │   ├── Prospective lenders see pattern
│   │   ├── Multiple denials signal
│   │   └── Further rejection likely
│   └── Score and confidence damage
│       ├── Score reduction: 5-10 points
│       ├── Confidence impact: Discouraging
│       ├── Confidence timing: Affects future plans
│       ├── Focus shift: Away from building
│       └── Momentum loss: Disrupts progress
├── Minimum Requirements
│   ├── Credit score: Varies by card
│   │   ├── Subprime: 300+
│   │   ├── Secured: 400+
│   │   ├── Fair credit: 550+
│   │   ├── Standard: 620+
│   │   ├── Good: 670+
│   │   ├── Excellent: 740+
│   │   └── Premium: 750+
│   ├── Credit history: Length required
│   │   ├── Subprime: None required
│   │   ├── Secured: Minimal (any)
│   │   ├── Standard: 1+ year
│   │   ├── Good: 2+ years
│   │   ├── Excellent: 3+ years
│   │   └── Premium: 5+ years
│   ├── Income requirements
│   │   ├── Subprime: $10,000+
│   │   ├── Secured: $12,000+
│   │   ├── Standard: $15,000+
│   │   ├── Good: $20,000+
│   │   ├── Excellent: $30,000+
│   │   └── Premium: $50,000+
│   └── DTI requirements
│       ├── Subprime: 60%+ acceptable
│       ├── Secured: 50%+ acceptable
│       ├── Standard: 43-50%
│       ├── Good: 36-43%
│       ├── Excellent: 28-36%
│       └── Premium: Below 28%
├── How to Avoid It
│   ├── Research first: Before applying
│   ├── Check requirements: On issuer website
│   ├── Assess honestly: Your eligibility
│   ├── Apply realistic: For achievable cards
│   ├── Target building: To reach higher tier
│   └── Plan timeline: For future applications
├── Research Resources
│   ├── Issuer websites: Official requirements
│   ├── Card review sites: Approval odds
│   ├── Reddit communities: User experiences
│   ├── Card comparison tools: Filtering features
│   └── Financial blogs: Expert insights
└── Strategic Approach
    ├── Identify: Current credit tier
    ├── Research: Cards within tier
    ├── Apply: For achievable options
    ├── Build: Credit and score
    ├── Plan: Progression to better cards
    └── Timeline: 6-12 month intervals
❓ Comprehensive FAQ Section – Semantic SEO Optimized
Search Intent Analysis and Entity Relationships
The following FAQs address various search intents related to credit card approval, credit building, and financial management in 2026.
General Credit Card Approval Questions
Q1: How long does a credit card approval take in 2026?
A: Modern credit card application processing in 2026 uses automated underwriting systems and real-time verification, resulting in significantly faster approval timelines compared to previous years.
Approval Timeline Breakdown:
- Instant decisions: 50-70% of applications (within minutes)
- Same-day decisions: 20-30% of applications (within hours)
- Conditional approval: 10-15% (requires 24-48 hours documentation)
- Manual review: 5-10% (up to 2 weeks)
- Physical card arrival: 7-10 business days after approval
- Digital card access: Often immediate with temporary numbers
Semantic Entities Involved:
- Decision Timeline (temporal factor)
- Automated Underwriting (technology process)
- Real-Time Verification (verification method)
- Conditional Approval (approval status)

Q2: What credit score do I need to get approved for a credit card?
A: Credit score requirements vary significantly by card type and credit card issuer, creating a tiered approval system based on creditworthiness assessment.
Credit Score Requirements by Card Category:
| Card Type | Minimum Score | Ideal Score | Best Odds Score |
|---|---|---|---|
| Secured Cards | 300 | 500+ | 550+ |
| Credit-Builder | 400 | 600+ | 650+ |
| Subprime/Fair | 550 | 620+ | 650+ |
| Standard/Good | 620 | 680+ | 700+ |
| Rewards | 670 | 720+ | 750+ |
| Premium | 740 | 780+ | 800+ |
| Luxury Elite | 750 | 800+ | 850 |
Additional Considerations:
- Newer cards: Stricter requirements than established issuers
- Online banks: More flexible than traditional banks
- Credit unions: Member benefits improve odds
- Alternative lenders: Consider alternative credit data
Q3: Can I get approved for a credit card with no credit history?
A: Yes, multiple pathways exist for credit approval even with no credit history, utilizing credit-building products and alternative credit data.
Approval Pathways for No-Credit Applicants:
- Secured Credit Cards
- Requires: Cash deposit equal to credit limit
- Approval likelihood: 95%+
- Timeline: Immediate processing
- Graduation: Typically 6-24 months
- Credit-Builder Cards
- Designed for: Limited credit history
- Approval likelihood: 85-90%
- Requirements: Flexible verification
- Features: Basic functionality
- Authorized User Status
- Requires: Existing account holder
- Impact: Immediate credit history
- Score increase: 50-100+ points
- Timeline: 1-2 months for bureau reporting
- Credit-Builder Loans
- Offered by: Credit unions
- Mechanism: Secured savings loan
- Result: Positive payment history
- Timeline: 6-12 months
- Alternative Credit Data Cards
- Consider: Utility payments, rent
- Verification: Alternative bureaus
- Approval: Possible without traditional credit
- Timeline: Growing in availability
Q4: How many credit cards should I apply for?
A: Application frequency and strategic spacing are critical to credit score management and approval success.
Recommended Application Strategy:
Optimal Approach:
- Frequency: One application every 3-6 months
- Reasoning: Minimizes hard inquiry impact
- Benefits: Demonstrates thoughtful planning
- Success rate: Highest per application
Alternative Approach (for rate shopping):
- Frequency: 2-3 applications within 45 days
- Counting: May count as single hard inquiry (same product type)
- Best for: Comparing rates on similar products
- Timeline: Only once per year maximum
Long-Term Portfolio Building:
- Year 1: 1-2 cards
- Year 2: 3-4 cards total
- Year 3+: 4-6 cards for optimal credit mix
- Spacing: 3-6 months between applications minimum
Factors Influencing Frequency:
- Credit score: Higher scores can apply more frequently
- Financial situation: Stability matters more than quantity
- Card strategy: Some deliberately space applications
- Approval odds: Lower scores need more conservative spacing
Q5: Does applying for a credit card hurt my credit score?
A: Yes, credit card applications generate hard inquiries that temporarily impact credit scores, but the damage is manageable with proper strategy.
Hard Inquiry Impact Analysis:
Immediate Impact:
- Score reduction: 5-10 points per inquiry
- Duration: Visible on report for 1 year
- Impact duration: Scoring impact for 3-6 months
- Recovery rate: Full recovery within 6-12 months
Compounding Effect:
- Single inquiry: Minimal impact
- Multiple inquiries (2-3): Moderate impact
- Multiple inquiries (4+): Significant impact
- Within 45 days: May count as one inquiry (same product)
Scoring Impact Timeline:
- Month 1: Worst impact (full deduction)
- Month 2-3: Reduced impact
- Month 4-6: Minimal impact
- Month 7-12: Nearly eliminated
- After 12 months: Inquiry removed from report
Mitigation Strategies:
- Space applications: 3-6 months apart
- Focus improvements: In between applications
- Build positive activity: New on-time payments
- Pay down balances: Reduce utilization
- Add authorized user status: Builds positive history
- Time passage: Most effective remedy
Long-Term Benefit Analysis:
- New credit account: Increases available credit
- Positive payment history: Begins building
- Credit mix: Improves overall portfolio
- Score benefit: Often exceeds inquiry damage within 6 months
Credit Score and History Management
Q6: How can I improve my credit score quickly?
A: Credit score improvement happens through targeted strategies focused on the highest-impact factors, with realistic timelines.
Fastest-Acting Improvement Strategies:
- Pay Down Credit Card Balances (2-4 weeks)
- Impact: 50-100+ point increase possible
- Mechanism: Reduces utilization ratio
- Speed: Changes appear in 1 billing cycle
- Method: Pay before statement closing date
- Best for: Immediate, visible improvement
- Dispute Credit Report Errors (1-2 months)
- Impact: 50-200+ points if significant error
- Mechanism: Removes negative/incorrect items
- Speed: 30-day investigation window
- Method: File dispute with credit bureau
- Best for: Recovering from errors
- Become Authorized User (1-2 months)
- Impact: 50-100+ points from positive account
- Mechanism: Adds account to your history
- Speed: Reports within 1-2 months
- Condition: Account holder must have excellent credit
- Best for: Immediate boost with right account
- Make On-Time Payments (2-3 months)
- Impact: 10-30 points improvement per month
- Mechanism: Improves payment history
- Speed: Progressive improvement
- Duration: Compounding over time
- Best for: Long-term, sustainable improvement
Timeline Expectations:
- 2-4 weeks: Utilization reduction impact
- 1-2 months: Error dispute resolution
- 6-8 weeks: Payment history improvement visible
- 3-6 months: Significant cumulative improvement (50-150 points)
- 12+ months: Major transformation (200+ points)
Q7: How long do negative items stay on my credit report?
A: Credit reporting timelines are governed by the Fair Credit Reporting Act (FCRA), with specific retention periods for different negative items.
Negative Item Reporting Timelines:
| Item Type | Reporting Period | Impact Timeline |
|---|---|---|
| Late Payments | 7 years from delinquency date | Impact decreases after 3-4 years |
| Collections | 7 years from original delinquency | Impact decreases after 2-3 years |
| Charge-offs | 7 years from original delinquency | Impact decreases after 2-3 years |
| Foreclosure | 7 years from foreclosure date | Impact decreases after 3-4 years |
| Bankruptcy Ch. 7 | 10 years from filing date | Can rebuild after 3-5 years |
| Bankruptcy Ch. 13 | 7 years from filing date | Can rebuild after 2-3 years |
| Tax Liens | 7 years from lien date | Can be removed earlier if paid |
| Civil Judgments | 7 years from judgment date | Varies by state (some 10+ years) |
Age and Impact Relationship:
- 0-6 months old: Most damaging
- 6 months – 1 year: Still very damaging
- 1-3 years: Significantly damaging
- 3-5 years: Moderately damaging
- 5-7 years: Minimally damaging
- 7+ years: Removed from report
Credit Score Recovery Timeline:
- 3-4 years: Can qualify for good credit cards
- 5-7 years: Can qualify for excellent credit
- 7+ years: Item removed, full recovery possible
Q8: Will checking my own credit score hurt my score?
A: No, checking your own credit score through soft inquiries has absolutely no impact on your credit score, allowing you to monitor freely.
Inquiry Types and Impact:
Soft Inquiries (No Score Impact):
- Your account review: By your bank/issuer
- Personal credit checking: Free services, apps
- Pre-qualification offers: From lenders
- Employment screening: By current/prospective employers
- Insurance underwriting: By insurance companies
- Frequency: Check as often as desired
- Duration: Not visible to other lenders
- Score impact: Zero
Hard Inquiries (Score Impact):
- Credit application: By lender
- Manual trigger: Credit card, loan, mortgage
- Score impact: 5-10 points per inquiry
- Visible to: Other lenders
- Duration: 1 year on report
- Frequency: Should space 3-6 months apart
Free Credit Monitoring Services:
- Credit Karma: Soft inquiries only
- Credit Sesame: Soft inquiries only
- Bank services: Most banks offer free scores
- Annual free reports: annualcreditreport.com
- Frequency: Check monthly or as often as desired
- Cost: Completely free
Recommendation:
- Check your own score: Monthly or quarterly
- Monitor changes: Track improvement progress
- Avoid hard inquiries: Only when applying for actual credit
- Use soft inquiries: For monitoring purposes only
- Benefit: Catch fraud, track progress, verify improvements
Application and Approval Process
Q9: What should I do if my credit card application is denied?
A: Credit card denial is not permanent; understanding denial reasons and taking corrective action significantly increases future approval chances.
Post-Denial Action Plan:
Immediate Actions (Within 24-48 hours):
- Request written denial notice (required by law)
- Call reconsideration line immediately
- Ask specific denial reason (required disclosure)
- Propose additional information that might help
- Listen carefully to any opportunities to reconsider
Analysis Phase (Days 2-7):
- Review denial reason carefully
- Check your credit report for errors
- Calculate DTI ratio accurately
- Assess income documentation freshness
- Identify specific improvement area
Improvement Phase (Weeks 2-12):
- Address the specific issue identified
- Credit score: Pay down balances, make on-time payments
- Income: Update with new documentation
- DTI: Pay down existing debts aggressively
- Timeline: Allow 4-6 weeks for improvements to report
Reapplication Strategy:
- Same issuer: Wait 30-90 days, reapply with improvements
- Different issuer: Can try after 2-3 weeks with different card
- Documented improvements: Show concrete progress
- Updated information: Provide fresh documentation
Success Factors:
- Common reasons for reconsideration approval: 10-30%
- Approval after reapplication: 30-40% with improvements
- Approval from different issuer: 40-60% with right card choice
- Timeline: Can occur within 3-6 months with effort
Q10: Can I have multiple credit cards?
A: Yes, having multiple credit cards is common and can benefit your credit score through credit mix and available credit increase, assuming responsible management.
Benefits of Multiple Credit Cards:
- Credit Score Benefits
- Available credit increase: Lowers utilization ratio
- Credit mix: Adds diversity to profile
- Payment history: More accounts = more positive history
- Account age mix: Helpful for score calculation
- Typical impact: 10-30 point improvement
- Financial Benefits
- Rewards diversification: Different rewards on different cards
- Category optimization: Match card to spending type
- Bonus stacking: Multiple signup bonuses
- Backup protection: If one card unavailable
- Spending flexibility: Multiple credit limits
- Practical Benefits
- Fraud protection: Card compromised = alternatives available
- Merchant acceptance: Some don’t take all cards
- Travel benefits: Different cards offer different perks
- Relationship building: Multiple issuer relationships
- Card features: Utilize specific benefits on each
Optimal Number of Cards:
| Credit Profile | Recommendation | Rationale |
|---|---|---|
| Building Credit | 1-2 cards | Focus on single card responsibility |
| Fair Credit | 2-3 cards | Establish diverse history |
| Good Credit | 3-4 cards | Optimize rewards and utilization |
| Excellent Credit | 4-6 cards | Maximize benefits and utilize perks |
| Very High Income | 5-8+ cards | Depending on complexity and needs |
Management Requirements:
- On-time payments: Required on ALL cards
- Utilization tracking: Monitor across all accounts
- Account monitoring: Fraud prevention on each
- Fee management: Justify annual fees
- Organization: Prevent missed payments
Risks of Multiple Cards:
- Overspending: Too many cards enable excess debt
- Missed payments: Higher chance of forgotten due date
- Complexity: Tracking becomes difficult
- Score impact: If not managed carefully (utilization)
- Interest debt: Balances across multiple cards compound
- Annual fees: Multiple premium cards = significant cost
Recommendation:
- Start with 1-2 cards: Master management
- Add additional cards: Only if managing current responsibly
- Increase gradually: Every 6-12 months
- Use strategically**: Each card for specific purpose
- Monitor actively**: All accounts regularly
Q11: Should I close credit card accounts I’m not using?
A: No, you should generally keep credit cards open even if unused, as closing credit accounts negatively impacts credit scores through multiple mechanisms.
Why Closing Cards Harms Credit Score:
- Reduced Available Credit
- Impact: Increases credit utilization ratio
- Example: Close $3,000 limit card, utilization jumps 10-20%+
- Score impact: 10-50+ point reduction
- Duration: Permanent until account removed
- Shortened Account Age
- Impact: Average account age decreases
- Effect: Old account history removed
- Score impact: 5-15 point reduction
- Duration: Years until account drops off (10 years)
- Reduced Credit Mix
- Impact: Fewer account types (minor)
- Effect: Less diversity in credit profile
- Score impact: 5 points (minimal)
- Duration: Until new account type added
- Account Removal Risk
- Impact: Account eventually removed from report
- Timeline: 10 years after closure
- Effect: Loss of history length
- Score impact: Ongoing throughout period
Calculation Impact Example:
Before Closure:
- Available credit: $10,000
- Current balance: $2,000 (20% utilization)
- Score: 750
After Closing $3,000 Card:
- Available credit: $7,000
- Current balance: $2,000 (29% utilization)
- Score impact: -10 to -30 points
- New score: 720-740
Exceptions When Closure May Be Acceptable:
- Predatory terms: Card with extremely unfavorable terms
- High annual fee: Unwarranted by benefits
- Fraud account: Compromised or fraudulently opened
- Excessive number: If truly can’t manage
- Financial hardship: Literally cannot afford to keep open
- Excellent score: Score so high a small hit is manageable
How to Keep Accounts Open:
- Use occasionally: Small purchase annually
- Set auto-payment: Small charge automatically
- Keep active: Regular low-balance usage
- Accept annual fee: If no annual fee available
- Monitor closely: Check for fraud, closures
Strategic Card Retention Plan:
| Card Type | Action | Frequency |
|---|---|---|
| High-APR Old Card | Keep active | Quarterly use |
| High Annual Fee | Negotiate waiver or close | Annual review |
| No Annual Fee | Keep indefinitely | Minimal annual use |
| Rewards Card | Use regularly | Weekly/monthly |
| Travel Perks | Use actively | As travel occurs |
Income and Financial Situation
Q12: What if my income is variable or I’m self-employed?
A: Self-employed income and variable income require additional documentation and different verification approaches, but approval is achievable with proper preparation.
Self-Employment Income Documentation:
Required Documents:
- Business tax returns: 2 years of prior returns
- Profit & loss statements: Current year
- Business bank statements: 2-3 recent months
- 1099 forms: From clients (if applicable)
- Business licenses: Proof of legitimacy
- Articles of incorporation: For corporations
Income Calculation Methods:
| Income Type | Calculation Method | Documentation |
|---|---|---|
| Sole Proprietor | Average of 2-year net income | Tax returns + P&L |
| S-Corp | Average of 2-year W-2 + distributions | Tax returns |
| LLC | Net income from tax returns | K-1 forms |
| Partnership | Your share of partnership income | K-1 forms |
| Freelancer | Average of 2-year 1099 income | 1099s + bank statements |
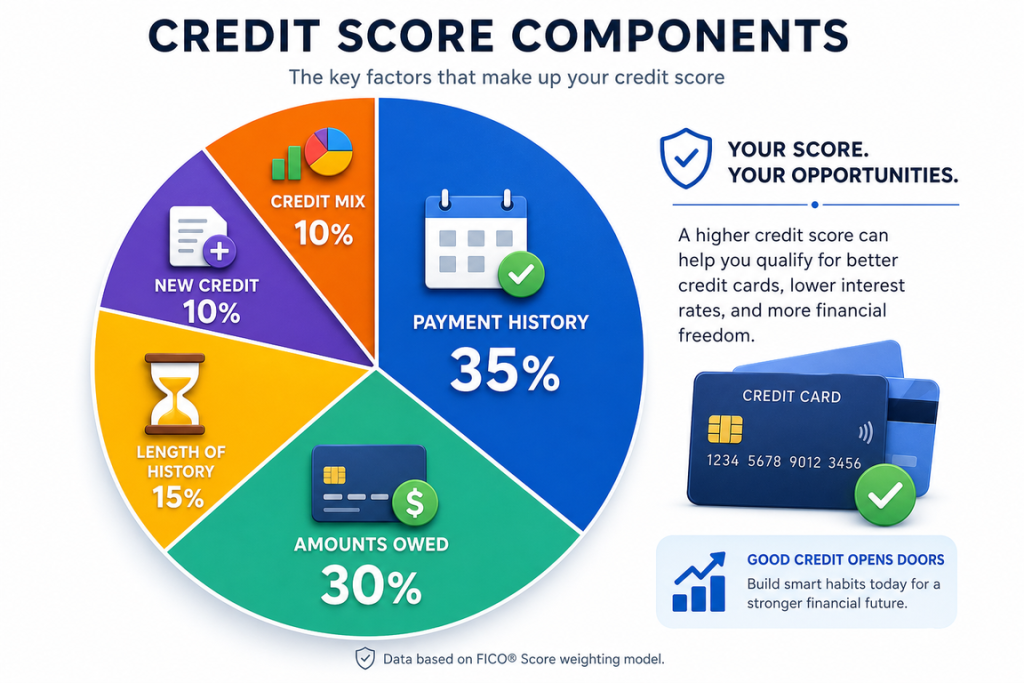
Variable Income Strategy:
Commission-Based Income:
- Calculate 2-year average: Shows consistency
- Recent pay stubs: Demonstrate current earning level
- Written verification: From employer/broker
- Bonus documentation: If reliable
Seasonal Income:
- Full-year reporting: Include all seasons
- Multi-year average: Smooths seasonal variations
- Documentation of patterns: Explains fluctuations
- Forecasts: If significant expected change
Side Business Income:
- Separate accounting: Clear separation from main job
- Dedicated business account: Shows seriousness
- Documentation: Receipts, invoices, payments
- Consistency: 2+ years of records
Lender Approach Differences:
Traditional Banks:
- Strict documentation: 2+ years required
- Conservative calculation: Lower of recent vs. average
- Verification methods: Direct verification
- Timeline: Longer review period
Online Lenders:
- Flexible documentation: May accept 1 year
- Open banking: Direct bank account analysis
- Real-time verification: Bank data directly
- Faster decisions: Hours vs. days
Credit Unions:
- Member benefits: More flexible
- Relationship consideration: History matters
- Community focus: Local self-employed support
- Personal connection: In-person help available
Q13: How do I verify my income during the application?
A: Income verification methods in 2026 combine traditional documentation with digital verification systems, allowing multiple verification pathways.
Income Verification Methods:
Traditional Documentation Methods:
- Recent Pay Stubs
- Requirement: 30-60 days old
- Information shown: Gross income, YTD earnings
- Advantages: Current income level, real-time proof
- Limitations: Won’t show previous income history
- Best for: W-2 employees with recent employment
- W-2 Forms
- Requirement: Past 2 years
- Information shown: Annual income history
- Advantages: Verified by IRS, shows stability
- Limitations: Past income (may have changed)
- Best for: Employment income verification
- Tax Returns
- Requirement: Past 2 years, signed copies
- Information shown: Income, deductions, net income
- Advantages: Comprehensive income picture
- Limitations: Most recent may be 6+ months old
- Best for: Self-employed, variable income
- Offer Letter
- Requirement: From current/future employer
- Information shown: Position, salary
- Advantages: Future income verification
- Limitations: Conditional on employment
- Best for: New employment income
Digital Verification Methods:
- Employment Verification Service
- System: Work Number (ADP)
- Process: Direct employer verification
- Timeline: Real-time or 24 hours
- Accuracy: Official employment records
- Coverage: Many large employers
- Open Banking Connection
- System: Direct bank account connection
- Process: Analyzes bank deposits
- Timeline: Instant analysis
- Advantage: Real-time income proof
- Emerging: Growing lender adoption
- IRS Verification
- System: E-Verify
- Process: IRS records access
- Timeline: Hours to days
- Accuracy: Official tax records
- Coverage: Limited to some lenders
- Third-Party Services
- Companies: VeriFone, eScore, others
- Process: Aggregated data analysis
- Timeline: Hours
- Information: Multi-source verification
- Growing: Increasingly available
Documentation Presentation Strategy:
Best Practices:
- Provide proactively: Submit with application
- Include multiple sources: Strengthens application
- Current documents: Recent dates matter
- Clear copies: Easily readable documents
- Both pages: Submit complete documents
- Highlighted details: Circle relevant information
Supporting Documentation:
- Bank statements: Show regular deposits
- Investment statements: Alternative income source
- Rental agreements: Rental income proof
- Social Security statements: Pension/benefits
- Divorce decree: Alimony/child support
- Letters of employment: Confirms position/stability
Q14: Does my spouse’s income count for credit card approval?
A: Spouse’s income may count toward household income in certain circumstances, depending on financial structure, marital status, and lender policies.
Spouse Income Considerations:
Community Property States:
- Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin
- Income status: Treated as community property
- Applicability: All marital income counts
- Advantage: Increases household income significantly
- Documentation: Both spouses’ income acceptable
Non-Community Property States:
- All other states
- Default status: Only applicant’s income counts
- Exception 1: Co-applicant with spouse
- Exception 2: Spouse applies jointly
- Exception 3: Spouse provides income documentation
- Advantage: Requires direct participation
Application Scenarios:
| Scenario | Spouse Income Counts | Documentation |
|---|---|---|
| Sole applicant | Maybe (varies by state) | Only your income needed |
| Co-applicant | Yes, both count | Both incomes documented |
| Joint application | Yes, household income | Combined documentation |
| Community property | Yes, automatically | May not need documentation |
| Co-signer only | No, co-signer separate | Co-signer’s income evaluated |
Strategic Considerations:
- Joint Application
- Advantage: Combine household income
- Disadvantage: Joint liability for both
- Credit: Both spouses’ credit affects approval
- Risk: Both liable if other doesn’t pay
- Best for: Equal income/responsibility
- Sole Applicant (Using Spouse Income)
- Advantage: Only you liable (if allowed)
- Disadvantage: Lender may require spouse documentation
- Complexity: Varies by lender and state
- Documentation: May need proof of spouse’s income
- Best for: Higher income spouse, lower credit score
- Co-Signer Approach
- Advantage: Spouse provides creditworthiness
- Disadvantage: Spouse co-liable
- Documentation: Co-signer’s credit/income verified
- Impact: Both credit scores affected
- Best for: Low credit score applicant, high-income spouse
Recommendation:
- Consult lender directly: Policies vary
- Know your state: Community property affects default
- Understand liability: Before choosing approach
- Document thoroughly: Support income claims
- Choose strategically: Based on your situation
Card Selection and Strategy
Q15: How do I choose the right credit card for my credit profile?
A: Choosing the appropriate credit card requires matching your credit score, credit history, income level, and spending patterns to the correct card category and specific card offering.
Credit Profile Matching Framework:
Credit Score Range: Below 620 (Poor Credit)
Card Categories Available:
- Secured Credit Cards (Recommended)
- Deposit requirement: Equal to credit limit
- APR range: 20-29%
- Annual fee: $0-75
- Graduation timeline: 6-24 months
- Best for: Building credit from scratch
- Examples: Capital One Secured, Discover Secured
- Credit-Builder Cards
- Credit limit: $200-1,000
- APR range: 15-25%
- Annual fee: $0-25
- Approval likelihood: 85-90%
- Best for: New to credit
- Examples: Various niche offerings
- Specialty Subprime Cards (Caution)
- APR range: 25-35%+
- Annual fees: $50-250
- Features: Minimal rewards
- Caution: Often predatory
- Avoid: High-fee options
Selection Strategy:
- Prioritize: Secured or builder cards
- Avoid: High annual fees
- Focus: Building history and on-time payments
- Minimize costs: Keep fees low
- Timeline: Graduate to better cards in 1-2 years
Q16: What’s the difference between a secured credit card and a regular credit card?
A: Secured credit cards and unsecured credit cards differ fundamentally in structure, requirements, and purpose, with secured cards serving as credit-building tools.
Secured Credit Card Mechanics:
Deposit Structure:
- Function: Collateral for credit issuer
- Amount: Usually equals credit limit
- Example: $500 deposit = $500 credit limit
- Storage: Held in savings account
- Interest: You earn interest on deposit
- Withdrawal: Cannot access until account graduated
- Returned: After graduation to unsecured status
Usage and Payments:
- Works like: Regular credit card
- Purchases: Normal charging privileges
- Bills paid from: Your own account (not deposit)
- Deposit: Never used for payments
- Interest: Charged on balances like any card
- Payments: Made same as unsecured card
Comparison Table:
| Feature | Secured Card | Unsecured Card |
|---|---|---|
| Deposit Required | Yes (collateral) | No |
| Credit Limit | Usually = deposit | Based on creditworthiness |
| Approval Likelihood | 90-95% | Varies (50-90%+) |
| APR Range | 15-29% | 10-28% |
| Annual Fee | $0-75 | $0-500 |
| Rewards | Minimal (1% or less) | Often significant |
| Credit Building | Excellent | Excellent |
| Graduation | 6-24 months | N/A |
Secured Card Graduation:
- Timeline: 6-24 months of responsible use
- Conditions: Perfect payment history, score improvement
- Process: Automatic or application-based
- Result: Card converted to unsecured
- Deposit: Returned or converted to credit line
- Impact: Credit-building success
Best Secured Card Features:
- Annual fee: Preferably $0
- Credit limit: Should be at least $500
- Reporting: Must report to all three bureaus
- Path to graduation: Clear conversion criteria
- Reputable issuer: Established financial institution
Q17: How should I use a new credit card to build credit most effectively?
A: Effective credit building with a new credit card requires deliberate usage patterns focused on establishing perfect payment history and maintaining low credit utilization.
Optimal Credit-Building Usage Strategy:
Monthly Usage Pattern:
- Make Regular Small Purchases
- Amount: $100-300 monthly
- Purpose: Show activity and responsible usage
- Examples:
- Groceries ($50)
- Gas ($40)
- Subscription service ($15)
- Utilities if available ($30)
- One larger item ($165)
- Frequency: Spread throughout month
- Benefit: Demonstrates consistent usage
- Keep Balance Low
- Target utilization: 5-10%
- Maximum: 30% of limit
- Example: $500 limit = keep balance under $50
- Timing: Before statement closing
- Strategy: Pay down before monthly closing date
- Impact: Reported utilization minimized
- Set Up Automatic Full Payment
- Amount: Full statement balance
- Timing: Before due date
- Method: Bank automatic payment
- Benefit: Never miss payment, no interest charges
- Result: Perfect payment history
- Timeline: Required indefinitely
- Monitor Monthly
- Check statements: Within days of receipt
- Review charges: Catch any fraud
- Verify payment posting: Confirm application
- Track utilization: See score impact
- Update budget: Adjust spending if needed
Timeline and Expected Results:
| Timeline | Actions | Expected Results |
|---|---|---|
| Month 1 | First purchase, setup auto-pay | Account established |
| Month 2-3 | Regular usage, full payments | Payment history starts |
| Month 4-6 | Continued usage, monitoring | Score begins improving |
| Month 7-12 | Consistent perfect payments | 30-50 point score increase |
| Month 12+ months | Request limit increase | Get $1,000+ limit |
Credit Building Do’s:
- ✓ Use card monthly for normal purchases
- ✓ Pay balance in full every month
- ✓ Pay early (before due date)
- ✓ Monitor account regularly
- ✓ Keep account active indefinitely
- ✓ Request limit increases after 12 months
- ✓ Celebrate score improvements
Credit Building Don’ts:
- ✗ Don’t carry monthly balance
- ✗ Don’t make unnecessary large purchases
- ✗ Don’t miss any payments
- ✗ Don’t apply for multiple cards immediately
- ✗ Don’t close card after payoff
- ✗ Don’t let card go completely unused
- ✗ Don’t ignore statements
Utilization Optimization Strategy:
Payment Timing Technique:
- Statement closing date: Usually 1st of month
- Purchase: Items through 28th
- Pay: On 28th-30th (before closing)
- Result: Lower balance reported to bureaus
- Due date: 25th of following month
- Advantage: Reported utilization minimized while using full period
Example Scenario:
- Credit limit: $1,000
- Month 1 purchases: $250
- Payment on 28th: $250
- Reported balance: Near $0
- Reported utilization: 0-2%
- Score impact: Maximized positive
Protection and Security
Q18: How are credit cards protected against fraud?
A: Credit card fraud protection in 2026 is comprehensive, offering multiple layers of protection through federal law, issuer policies, and advanced fraud detection systems.
Fraud Protection Framework:
Federal Law Protections (FCRA):
- Liability limit: $50 maximum per fraudulent transaction
- Condition: Must report before issuer discovers fraud
- Industry practice: Most issuers waive the $50
- Result: Zero liability in most cases
- Enforcement: Card company’s responsibility
Issuer Zero-Liability Policies:
- Coverage: 100% of fraudulent charges
- Condition: Reported timely (usually 60-90 days)
- Process: Card company reverses fraudulent charges
- Timeline: Typically 10 business days
- Proof: Documentation requirements minimal
Advanced Fraud Detection:
- Machine Learning Algorithms
- Monitor: Every transaction in real-time
- Flag: Unusual spending patterns
- Block: Suspicious transactions immediately
- Reduce: False positives through AI
- Result: Catches fraud within seconds
- Behavioral Analysis
- Track: Your normal spending patterns
- Compare: New transactions against patterns
- Alert: Unusual location/amount/time
- Block: Transactions outside normal behavior
- Adaptive: Learns your actual patterns over time
- Geographic Verification
- Detect: Impossible geography (travel speed)
- Example: Charge in NY then 2 hours later in Florida
- Verify: Unusual location for cardholder
- Block: Geographically impossible transactions
- Allow: When you travel (with notification)
- Merchant Verification
- Check: Against known fraud merchants
- Verify: Merchant legitimacy
- Block: Known fraudulent merchants
- Alert: Unusual merchant types
- Update: Database constantly updated
Fraud Response Process:
Step 1: Discovery
- You notice: Unauthorized charge
- Card alerts: Auto-notification of large transaction
- Timeline: Report within 60 days for full protection
- Method: Online, phone, or in-person
Step 2: Report
- Contact card issuer: Fraud department
- Information: Provide charge details
- Claim: State it’s unauthorized
- Report: Disputes in writing (also acceptable)
- Timeline: Issuer must investigate within 30 days
Step 3: Investigation
- Issuer investigates: With merchant and payment network
- Timeline: Up to 30 days
- Process: Documented thoroughly
- Result: Fraud verified or disputed
Step 4: Resolution
- Chargeback initiated: If merchant can’t prove authorization
- Refund issued: Funds returned to your account
- Timeline: 5-10 business days typical
- Record: Updated with card status
Temporary Card:
- Replacement: Issued immediately while fraudulent card cancelled
- Interim: Digital card numbers for urgent purchases
- Continuity: Your credit access continues
- Timeline: Physical replacement arrives in 7-10 days
Protection Advantages Over Debit:
- Credit cards: Zero liability, quick resolution
- Debit cards: Limited liability, longer dispute process
- Bank accounts: No protection guarantee
- Cash: No protection
- Recommendation: Credit cards most protected payment method
Q19: How should I monitor my credit card account for fraud?
A: Fraud monitoring combines personal vigilance with automated alerts and credit monitoring services to catch fraudulent activity quickly.
Multi-Layer Monitoring Strategy:
Layer 1: Personal Statement Review
- Frequency: Upon receipt (monthly)
- Process: Review all transactions
- Look for: Unknown merchants, unusual amounts
- Compare: Against your calendar/activities
- Timeline: Immediate action if fraudulent
Layer 2: Online Account Access
- Check: Weekly or biweekly
- View: Real-time transactions
- Monitor: Balance and available credit
- Speed: Catch fraud faster than monthly
- Advantage: Catch fraud within days vs. weeks
Layer 3: Card Issuer Alerts
- Set alerts: For transactions over amount (e.g., $100)
- Set alerts: For international transactions
- Set alerts: For specific merchant categories
- Receive: Email, text, or push notification
- Response: Review immediately upon alert
Layer 4: Credit Monitoring Services
- Examples: Credit Karma, Credit Sesame, Credit.com
- Monitor: Credit report daily
- Alert: New accounts, inquiries, changes
- Fraud detection: Alerts to fraud signals
- Cost: Usually free
- Coverage: Broader than single card
Layer 5: Credit Bureau Fraud Alerts
- Types: Fraud alert, credit freeze, fraud victim statement
- Fraud alert: Notifies creditors to verify identity
- Duration: 1 year (renewable)
- Effect: Makes unauthorized credit harder to obtain
- Cost: Free
Fraud Monitoring Tools:
Built-In Card Tools:
- Transaction categorization: By merchant
- Balance alerts: When balance exceeds threshold
- Payment reminders: Upcoming due dates
- Spending reports: Category breakdowns
- Merchant notifications: Recurring charges
Third-Party Tools:
- ID theft protection services: Comprehensive monitoring
- Document storage: Secure financial records
- Password managers: Secure credential storage
- Virtual card numbers: Single-use card numbers
- Cost: Often $5-15 monthly
Recommended Monitoring Schedule:
| Activity | Frequency | Method |
|---|---|---|
| Check online account | Weekly | App or website |
| Review alert emails | Daily | Check email |
| Check credit report | Monthly | Free monitoring service |
| Review statement | Monthly | Upon receipt |
| Monitor for alerts | Ongoing | Notification settings |
| Annual credit check | Yearly | All 3 bureaus |
Red Flags to Monitor:
- Account Activity
- Unknown merchants
- Repeated small charges (testing card)
- Foreign transactions when you didn’t travel
- Duplicate transactions
- Round-dollar amounts (common fraud pattern)
- Account Changes
- Address changes you didn’t make
- Pending name changes
- New authorized users you didn’t authorize
- Card replacement orders you didn’t request
- Account settings changes
- Credit Activity
- New accounts opened (fraud signal)
- New inquiries (attempted fraud)
- Collections accounts (identity theft)
- Late payments you didn’t make
- Address changes on report
Immediate Actions if Suspected Fraud:
- Call card issuer immediately
- Number: On back of card
- Report: Unauthorized transaction
- Request: Card cancellation
- Ask: Temporary card issuance
- Freeze credit (if identity theft)
- Contact: All three bureaus
- Process: Place fraud alert
- Result: Prevents fraudulent accounts
- Duration: 90 days-7 years
- File police report (if identity theft)
- File: FTC Identity Theft Report
- Location: Police department
- Document: For creditors
- Reference: Use in disputes
- Dispute charges
- Method: In writing to card issuer
- Timeline: Within 60 days for protection
- Supporting: Any documentation
- Follow-up: Monitor resolution