Homeowners Insurance Quotes: How to Compare Coverage and Find the Right Policy
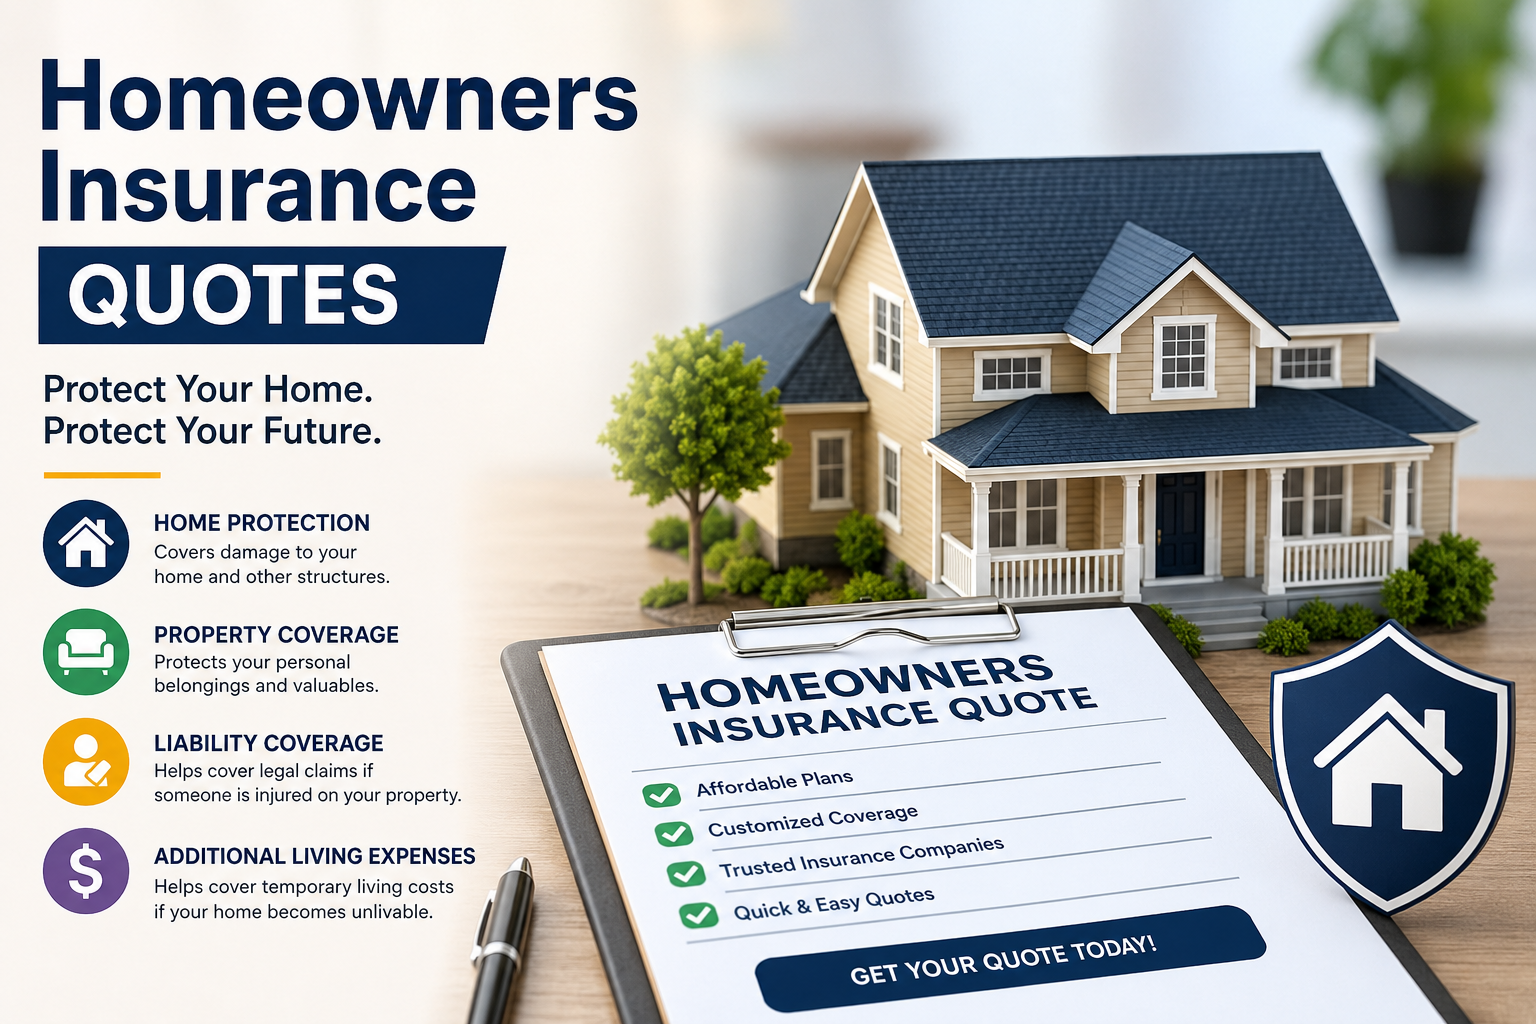
Buying a home is one of the biggest financial commitments many people make. Homeowners insurance can help protect that investment against certain unexpected events, including covered property damage, theft, and liability claims.
If you’re searching for homeowners insurance quotes, it’s important to look beyond the price. Two policies can have very different premiums while offering different coverage limits, deductibles, exclusions, and protections.
This guide explains how homeowners insurance quotes work, what affects your rate, how to compare policies, and practical ways to potentially reduce your insurance costs.
What Is a Homeowners Insurance Quote?
A homeowners insurance quote is an estimate of how much an insurance company may charge you for a specific level of coverage.
When requesting a quote, an insurer typically asks for information about your home, location, property characteristics, desired coverage, deductible, and other relevant factors.
The final premium may differ from the initial quote after the insurer verifies the information and completes its underwriting process.
A quote usually gives you an opportunity to compare:
- Estimated annual or monthly premium
- Dwelling coverage
- Personal property coverage
- Personal liability coverage
- Additional living expense coverage
- Deductible
- Optional coverage
- Policy exclusions and limitations
What Does Homeowners Insurance Cover?
A standard homeowners policy can provide several types of protection, although exact coverage varies by insurer and policy.
Dwelling Coverage
Dwelling coverage is designed to help pay for repairing or rebuilding the insured home’s physical structure after certain covered losses.
This can include parts of the home such as:
- Walls
- Roof
- Floors
- Built-in appliances
- Attached structures
The coverage amount should generally be based on the estimated cost to rebuild the home rather than simply its market value.
Other Structures
Some policies provide coverage for structures on the property that are separate from the main house.
Examples may include:
- Detached garages
- Fences
- Sheds
- Certain other detached structures
Coverage limits and exclusions vary by policy.
Personal Property
Personal property coverage can help protect belongings after certain covered losses.
Examples include:
- Furniture
- Clothing
- Electronics
- Appliances
- Certain personal valuables
High-value items such as jewelry, collectibles, or expensive equipment may have special limits, so additional coverage may be appropriate in some circumstances.
Personal Liability
Liability coverage can help protect you financially if you are legally responsible for certain injuries or property damage involving other people.
For example, if a visitor is injured on your property and you are legally liable, your policy may provide coverage for eligible expenses and legal costs, subject to the policy terms and limits.
Additional Living Expenses
If a covered event makes your home temporarily unlivable, some homeowners policies may help pay certain additional living expenses while repairs are being completed.
This can potentially include expenses such as temporary accommodation and increased food costs, depending on the policy.
What Doesn’t Homeowners Insurance Usually Cover?
One of the most important parts of comparing homeowners insurance quotes is understanding exclusions.
A standard policy does not necessarily cover every type of damage.
Common exclusions or limitations may include certain losses caused by:
- Flooding
- Earthquakes
- Normal wear and tear
- Maintenance problems
- Certain pest infestations
- Intentional damage
Flood insurance, for example, is generally separate from standard homeowners insurance.
Because exclusions differ between policies, always read the policy documents carefully before purchasing coverage.
How Much Do Homeowners Insurance Quotes Cost?
There is no single price for homeowners insurance because premiums depend on many variables.
An insurer may consider factors such as:
- Location of the property
- Replacement cost of the home
- Age and condition of the house
- Roof age and construction
- Deductible
- Coverage limits
- Claims history
- Local weather and catastrophe risks
- Security and safety features
- Credit-based insurance information where permitted by law
- Selected optional coverage
For this reason, two homeowners with similar-looking properties can receive very different quotes.
How to Get Homeowners Insurance Quotes
Getting several quotes can help you understand the market and compare coverage.
Step 1: Gather Your Home Information
Before requesting quotes, collect basic information about your property.
You may need:
- Home address
- Year built
- Square footage
- Number of bedrooms and bathrooms
- Roof age
- Construction type
- Heating system
- Security systems
- Recent renovations
- Estimated value of personal belongings
Having accurate information can make the quoting process easier.
Step 2: Determine Your Coverage Needs
Think about how much coverage you may need for the home, personal belongings, liability, and other risks.
Avoid choosing coverage solely based on the lowest price.
A policy that saves money upfront may leave you with insufficient protection after a major covered loss.
Step 3: Compare Multiple Insurance Companies
Request quotes from several insurers or work with an independent insurance agent who can compare available options.
When comparing quotes, make sure the policies have similar:
- Coverage limits
- Deductibles
- Optional endorsements
- Property protections
- Liability limits
Otherwise, you may be comparing different levels of protection.
Step 4: Review the Policy Details
Before purchasing, carefully review the declarations page, coverage limits, deductibles, exclusions, and conditions.
Ask the insurer about anything you don’t understand.
How to Get Cheaper Homeowners Insurance Quotes
Homeowners may be able to reduce premiums through several strategies.
Increase Your Deductible
Choosing a higher deductible can sometimes reduce your premium. However, you should make sure you could comfortably pay that deductible after a covered loss.
Bundle Insurance Policies
Some insurers offer discounts when customers purchase homeowners and auto insurance from the same company.
Improve Home Security
Security systems, smoke detectors, burglar alarms, and other protective measures may qualify for discounts with some insurers.
Maintain Your Home
Keeping the roof, electrical system, plumbing, heating, and other major components in good condition can help reduce certain risks.
Ask About Available Discounts
Insurance companies may offer discounts based on factors such as:
- Home security
- New construction
- Claims-free history
- Policy bundling
- Protective devices
- Certain membership or affiliation programs
Discount availability varies by insurer and location.
Replacement Cost vs. Actual Cash Value
Understanding this difference is important when comparing homeowners insurance quotes.
Replacement cost coverage generally considers the cost of replacing damaged property with similar new property, subject to policy terms and limits.
Actual cash value generally accounts for depreciation when determining the value of damaged property.
For example, if an older television is destroyed in a covered event, an actual cash value calculation may account for its age and depreciation, while replacement cost coverage may provide more toward replacing it, depending on the policy.
Always check how your policy values the home and personal property.
Why Your Location Matters
Location can have a major effect on homeowners insurance premiums.
Insurance companies evaluate the risks associated with an area, which can include:
- Severe storms
- Hurricanes
- Tornadoes
- Wildfires
- Hail
- Theft
- Local construction costs
- Availability of emergency services
A homeowner in an area with frequent severe weather may receive higher quotes than someone with a similar property in a lower-risk location.
Homeowners Insurance Quotes by State
Insurance prices can vary significantly across the United States.
For example, homeowners in states exposed to hurricanes, coastal storms, wildfires, or other severe weather may face different pricing and coverage options than homeowners in lower-risk areas.
When comparing quotes, search specifically for your state and ZIP code because statewide averages don’t necessarily reflect what you’ll personally pay.
Questions to Ask Before Buying a Policy
Before choosing an insurance policy, consider asking:
- What exactly does this policy cover?
- What are the major exclusions?
- How much is the deductible?
- Is the home insured for replacement cost?
- How is personal property valued?
- Are expensive valuables subject to special limits?
- Is flood damage covered?
- Are there separate deductibles for hurricanes or other disasters?
- What liability limit is included?
- Are there discounts available?
- How will my premium change after filing a claim?
- What optional coverage is available?
Getting clear answers can help you avoid unpleasant surprises later.
Homeowners Insurance Quotes: What Should You Compare?
Don’t compare quotes based on premium alone.
| Feature | Why It Matters |
|---|---|
| Premium | Determines your regular insurance cost |
| Deductible | Determines your out-of-pocket cost for a covered claim |
| Dwelling coverage | Helps protect the home’s structure |
| Personal property | Protects eligible belongings |
| Liability coverage | Helps with certain liability claims |
| Additional living expenses | May help if a covered loss makes the home unlivable |
| Exclusions | Shows what isn’t covered |
| Optional endorsements | Can add specialized protection |
| Claims service | Important when you actually need the insurer |
Final Thoughts
Finding the best homeowners insurance quotes isn’t simply about finding the cheapest policy. The right choice should provide appropriate protection for your home, belongings, and financial situation at a price you can afford.
Start by gathering accurate property information, determine the coverage you need, request multiple quotes, and compare policies with similar coverage limits and deductibles.
Most importantly, read the exclusions and limitations before purchasing. Insurance is designed to protect you against covered risks, and understanding exactly what your policy does and doesn’t cover can be just as important as the premium you pay.
This article is for general educational purposes only and does not constitute insurance, financial, or legal advice. Coverage, pricing, eligibility, and insurance requirements vary by insurer, state, and individual circumstances.