Introduction
Personal loans with low interest rates are one of the most affordable ways to borrow money for emergencies, debt consolidation, home improvements, education, medical expenses, or major life events. Choosing the right lender can save you thousands of dollars over the life of your loan.
With banks, credit unions, and online lenders competing for customers in 2026, borrowers have more opportunities than ever to secure low-interest personal loans. However, the lowest advertised rates are usually available only to borrowers with excellent credit scores and strong financial histories.
This guide explains everything you need to know about finding the best low-interest personal loan.
Table of Contents
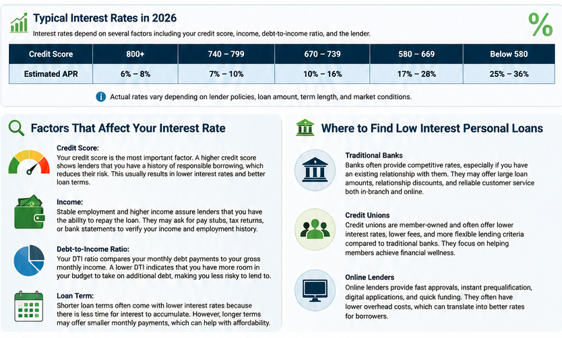
📌 What Is a Personal Loan?
A personal loan is an unsecured loan that allows borrowers to receive a lump sum of money and repay it in fixed monthly installments over a specific period.
Unlike mortgages or auto loans, personal loans generally do not require collateral.
Most lenders offer loan amounts ranging from:
- 💵 $1,000 to $100,000
- 📅 Repayment terms from 12 to 84 months
- 📉 Fixed interest rates
- 💳 No collateral required (in most cases)
⭐ Benefits of Low Interest Personal Loans
💰 Lower Monthly Payments
Lower interest rates reduce your monthly payment, making your loan easier to manage.
Advantages include:
- More affordable repayments
- Less financial stress
- Better monthly budgeting
- Faster debt payoff options
📉 Save Thousands in Interest
Even a small reduction in APR can result in significant savings.
For example:
- Loan Amount: $20,000
- Loan Term: 5 Years
At 8% APR:
- Total Interest ≈ $4,330
At 12% APR:
- Total Interest ≈ $6,694
Potential savings exceed $2,300 over the life of the loan.
💳 Debt Consolidation
Many borrowers use personal loans to combine multiple high-interest debts into one manageable monthly payment.
Common debts include:
- Credit cards
- Medical bills
- Payday loans
- Store financing
- Personal lines of credit
Benefits include:
- One payment each month
- Lower interest costs
- Improved credit utilization
- Easier financial management
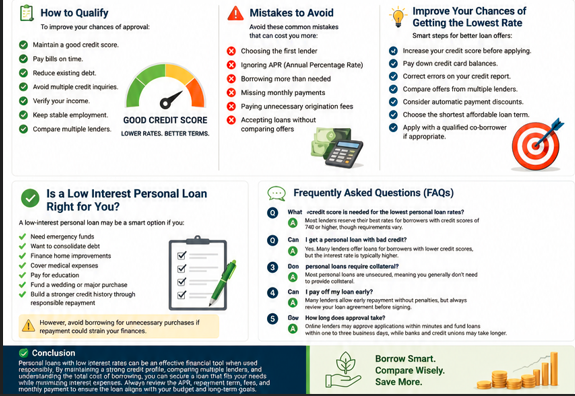
📊 Typical Interest Rates in 2026
Interest rates depend on several factors.
| Credit Score | Estimated APR |
|---|---|
| 800+ | 6%–8% |
| 740–799 | 7%–10% |
| 670–739 | 10%–16% |
| 580–669 | 17%–28% |
| Below 580 | 25%–36% |
Actual rates vary depending on lender policies, income, debt-to-income ratio, and market conditions.
🔍 Factors That Affect Your Interest Rate
Several factors determine the rate you’ll receive.
✅ Credit Score
Your credit score is one of the most important factors.
Higher credit scores usually qualify for:
- Lower APR
- Higher loan amounts
- Longer repayment terms
- Faster approval
💼 Income
Stable employment and higher income reassure lenders that you can repay the loan.
Lenders often verify:
- Employment history
- Salary
- Tax returns
- Bank statements
📈 Debt-to-Income Ratio
The debt-to-income (DTI) ratio compares your monthly debt payments to your monthly income.
Lower DTI generally improves approval chances and may help you secure better interest rates.
🕒 Loan Term
Shorter loan terms often come with lower interest rates.
For example:
- 2-year loan → Lower APR
- 5-year loan → Moderate APR
- 7-year loan → Higher overall interest
🏦 Where to Find Low Interest Personal Loans
Several financial institutions offer competitive rates.
Traditional Banks
Banks often provide:
- Competitive rates
- Large loan amounts
- Relationship discounts
- Reliable customer service
Credit Unions
Credit unions frequently offer:
- Lower APRs
- Lower fees
- Flexible underwriting
- Personalized service
Online Lenders
Online lenders have become increasingly popular because they offer:
- Fast approvals
- Instant prequalification
- Digital applications
- Quick funding
- Competitive rates
📋 How to Qualify
To improve your chances of approval:
- Maintain a good credit score.
- Pay bills on time.
- Reduce existing debt.
- Avoid multiple credit inquiries.
- Verify your income.
- Keep stable employment.
- Compare multiple lenders.
🚫 Mistakes to Avoid
Many borrowers pay more than necessary because they make avoidable mistakes.
Avoid:
- Choosing the first lender
- Ignoring APR
- Borrowing more than needed
- Missing monthly payments
- Paying unnecessary origination fees
- Accepting loans without comparing offers
📈 Improve Your Chances of Getting the Lowest Rate
Here are practical tips:
- Increase your credit score before applying.
- Pay down credit card balances.
- Correct errors on your credit report.
- Compare offers from multiple lenders.
- Consider automatic payment discounts.
- Choose the shortest affordable repayment term.
- Apply with a qualified co-borrower if appropriate.
💡 Is a Low Interest Personal Loan Right for You?
A low-interest personal loan may be a smart option if you:
- Need emergency funds
- Want to consolidate debt
- Finance home improvements
- Cover medical expenses
- Pay for education
- Fund a wedding or major purchase
- Build a stronger credit history through responsible repayment
However, avoid borrowing for unnecessary purchases if repayment could strain your finances.
❓ Frequently Asked Questions (FAQs)
What credit score is needed for the lowest personal loan rates?
Most lenders reserve their best rates for borrowers with credit scores of 740 or higher, though requirements vary.
Can I get a personal loan with bad credit?
Yes. Many lenders offer loans for borrowers with lower credit scores, but the interest rate is typically higher.
Do personal loans require collateral?
Most personal loans are unsecured, meaning you generally don’t need to provide collateral.
Can I pay off my loan early?
Many lenders allow early repayment without penalties, but always review your loan agreement before signing.
How long does approval take?
Online lenders may approve applications within minutes and fund loans within one to three business days, while banks and credit unions may take longer.
Conclusion
Personal loans with low interest rates can be an effective financial tool when used responsibly. By maintaining a strong credit profile, comparing multiple lenders, and understanding the total cost of borrowing, you can secure a loan that fits your needs while minimizing interest expenses. Before signing any agreement, review the APR, repayment term, fees, and monthly payment to ensure the loan aligns with your budget and long-term financial goals.