Target keywords used in this post: personal loan interest rate, personal loan vs credit card, low interest personal loan, credit card interest rate, personal loan rates. Personal Loan Interest Rate vs. Credit Card: Which Costs You Less?
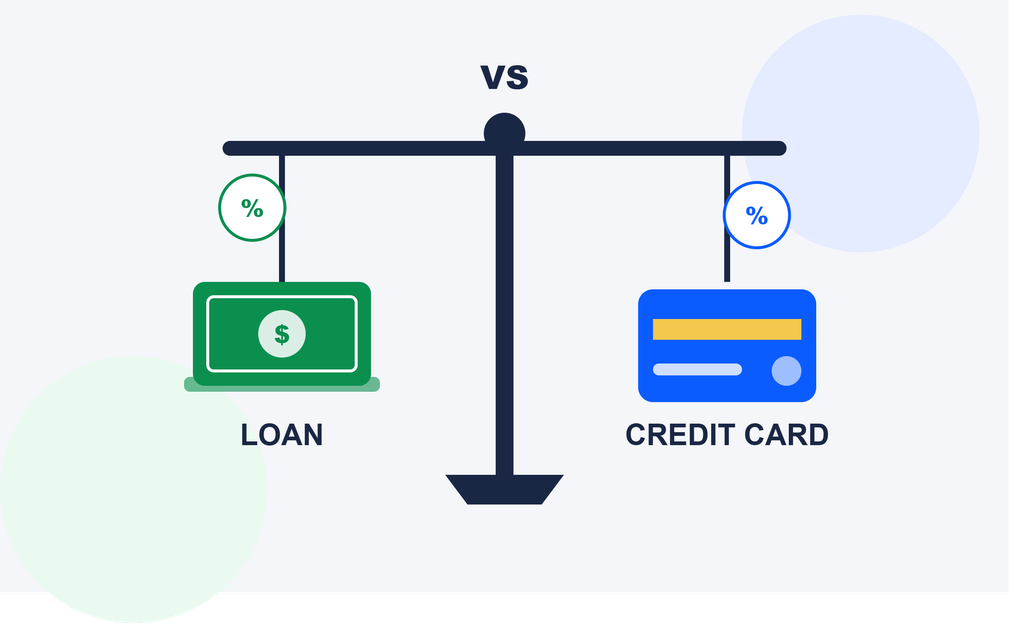
When you need to borrow money, the two most common options people compare are a personal loan and a credit card. Both let you access funds you don’t currently have, but the way they charge interest — and how that affects your total cost — is very different. Here’s a clear breakdown of how they stack up.
Table of Contents
The Core Difference: How Interest Is Calculated
A personal loan typically comes with a fixed interest rate applied to a fixed loan amount, repaid in equal monthly installments over a set term. You know from day one exactly what you’ll pay each month and when the loan will be fully paid off.
A credit card, on the other hand, charges interest on a revolving balance — the amount changes as you spend and pay it down. If you carry a balance month to month, interest compounds on whatever’s left, which means the total cost can grow if you’re only making minimum payments.
Typical Rate Ranges
Exact rates vary by lender, credit score, and country, but as a general pattern:
- Personal loans tend to carry lower interest rates than credit cards, especially for borrowers with good to excellent credit. Rates are often in the high single digits to low double digits (APR), though this varies widely by lender and market.
- Credit cards typically carry higher interest rates, frequently landing in the high teens to mid-20s (APR) range, particularly for standard or rewards cards.
This gap is the main reason personal loans are often recommended for paying off existing credit card debt — a strategy sometimes called debt consolidation.
Where Credit Cards Actually Win
Despite the higher interest rates, credit cards aren’t always the worse option — it depends on how you use them:
- If you pay your balance in full each month, you avoid interest entirely, making a credit card effectively free to use (aside from any annual fee).
- Flexibility — credit cards work well for ongoing or unpredictable expenses, since you’re not locked into a fixed repayment schedule.
- Rewards and cashback — many cards offer points, miles, or cashback that can offset costs if used responsibly.
- Building credit history — regular, on-time credit card payments can help build your credit profile over time.
Where Personal Loans Actually Win
- Lower rates for larger, planned expenses — if you need a specific amount for something like debt consolidation, a major purchase, or home repairs, a personal loan’s lower fixed rate usually costs less over time.
- Predictability — fixed monthly payments make budgeting easier, since the payment amount and payoff date don’t change.
- A clear end date — unlike a revolving credit card balance that can carry on indefinitely, a personal loan has a defined term after which it’s fully paid off.
A Simple Way to Decide
Ask yourself these questions:
- Do I know the exact amount I need to borrow? If yes, a personal loan’s fixed structure is usually a better fit.
- Can I realistically pay this off within a few months? If yes, a credit card (especially one with a 0% introductory offer, where available) might cost less overall.
- Am I using this to pay off existing high-interest debt? A personal loan is often cheaper here, since it can replace multiple high-rate balances with one lower, fixed rate.
- Do I want flexibility for ongoing or unpredictable spending? A credit card fits better than a fixed-term loan.
Quick Comparison Table
| Loan Personal | Card Credit | |
|---|---|---|
| Typical interest rate | Lower (varies by credit score) | Higher (varies by card and credit score) |
| type Rate | fixed Usually | Usually variable |
| Repayment | Fixed monthly payments, set term | Flexible minimum payments, revolving |
| Best for | Large, one-time, planned expenses | Smaller, flexible, or short-term spending |
| Risk of growing balance | Low — balance decreases on schedule | Higher — balance can grow if only minimums are paid |
Bottom Line
If you’re borrowing a specific amount and want predictable payments at a lower rate, a personal loan is usually the cheaper route — particularly for consolidating existing credit card debt. If you’re able to pay off your spending quickly or need flexibility for smaller, variable expenses, a credit card can work out just as well, or better, especially if you’re earning rewards along the way. The right choice really comes down to how much you’re borrowing, how fast you can repay it, and how disciplined you are about paying down the balance.
Personal Loan Interest Rates Explained: What to Know Before You Borrow