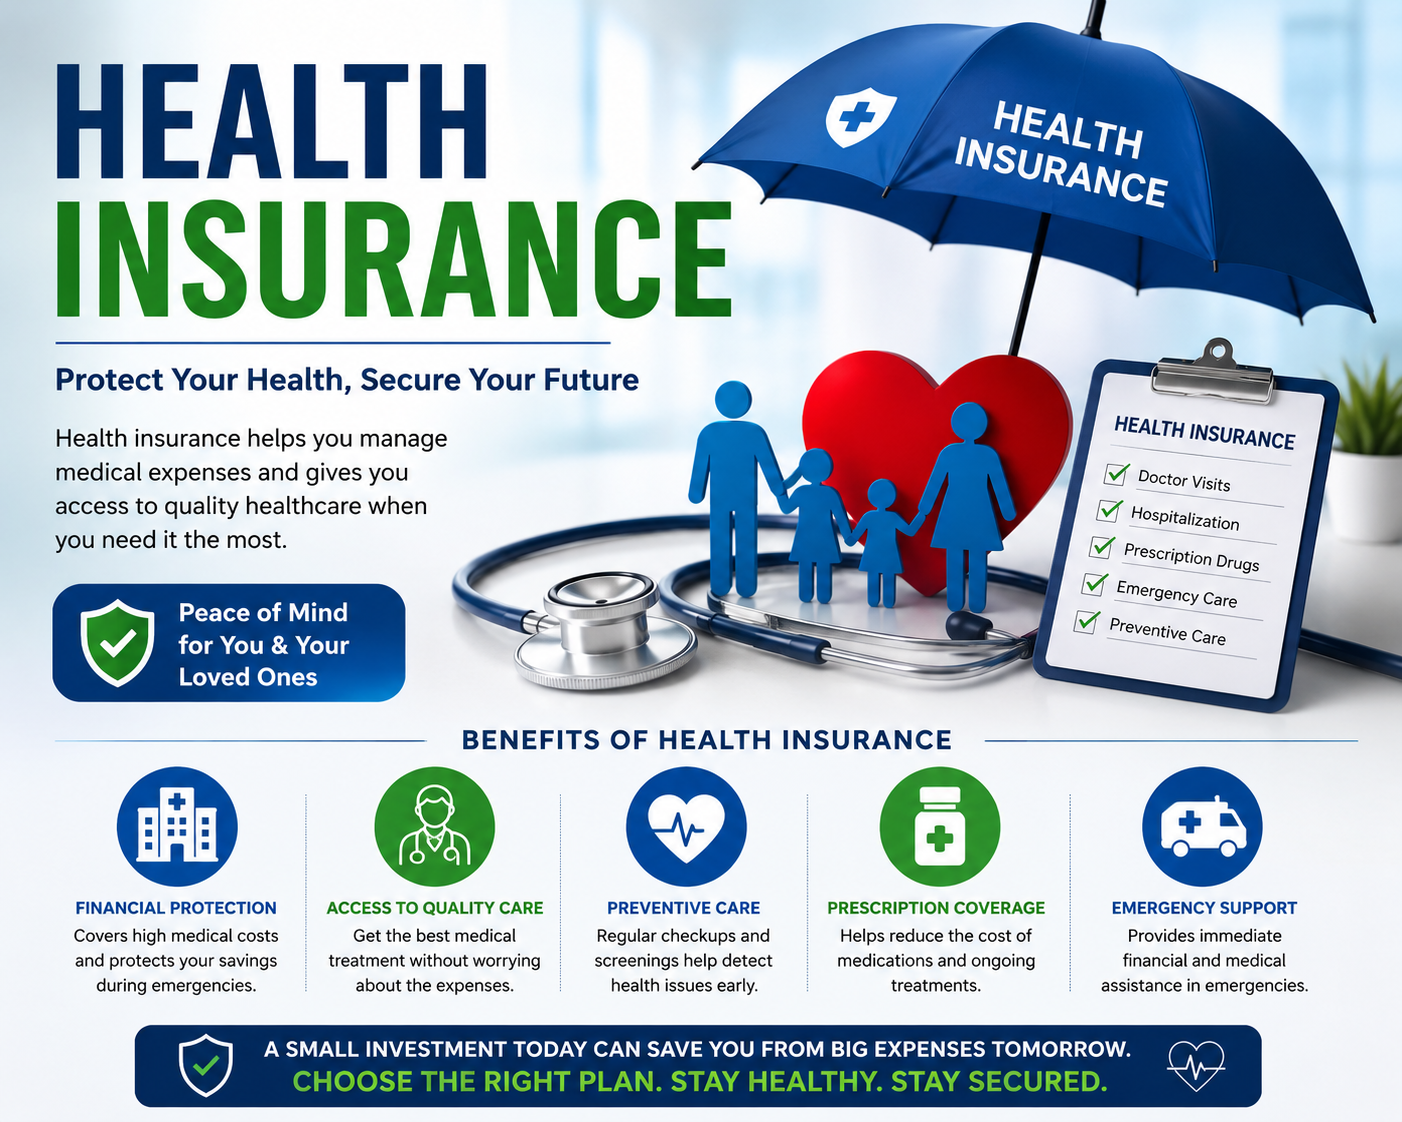
Health insurance is one of the most important forms of financial protection for individuals and families in the United States and across Europe. Medical care can be expensive, especially when unexpected emergencies, hospital stays, surgeries, prescription medications, or long-term treatments are involved. A suitable health insurance plan can help reduce eligible healthcare expenses and make medical services more financially manageable.
Whether you are looking for affordable health insurance, private health insurance, individual health insurance, family health insurance, or coverage through an employer, understanding how a policy works is essential before making a decision.
This complete guide explains health insurance coverage, premiums, deductibles, copayments, coinsurance, provider networks, healthcare costs, and the important factors to consider when comparing insurance plans.
💡 Important: Health insurance plans, benefits, eligibility rules, and healthcare systems vary by country, state, insurer, and individual circumstances. Always review the official policy documents before choosing coverage.
Table of Contents
🩺 What Is Health Insurance?
Health insurance is a financial protection arrangement designed to help individuals and families manage eligible medical and healthcare expenses. Depending on the insurance policy, coverage may help pay for doctor visits, hospital treatment, emergency care, prescription drugs, preventive services, specialist appointments, surgery, and other healthcare services.
Instead of paying the full cost of every eligible medical service yourself, you typically share certain costs with the health insurance provider according to the terms of your plan.
For example, you may pay a monthly premium to maintain your coverage. When you receive healthcare services, you may also be responsible for a deductible, copayment, or coinsurance amount. The exact amount depends on the policy and the type of medical care you receive.
Health insurance is particularly important because healthcare costs can be unpredictable. A routine doctor appointment may be affordable, but emergency treatment or hospitalization can create significant financial pressure without adequate coverage.
For individuals in the United States, health insurance options may include employer-sponsored plans, individual coverage, family plans, private insurance, and government-supported healthcare programs for eligible individuals. European healthcare systems differ significantly between countries, with a combination of public healthcare, statutory insurance, and private coverage depending on the location.
⚙️ How Does Health Insurance Work?
Health insurance generally works by dividing eligible healthcare costs between the insured person and the insurance provider.
When you enroll in a health insurance plan, you agree to pay certain costs to maintain coverage. In return, the insurer may contribute toward eligible healthcare expenses based on the policy’s rules, benefits, limitations, provider network, and cost-sharing structure.
Understanding the following terms can make it easier to compare health insurance plans.
💳 Premium
- 💰 Regular cost of maintaining coverage: A health insurance premium is the amount you pay regularly to keep your policy active. In many cases, premiums are paid monthly, although payment schedules can vary depending on the insurer or employer.
The premium is usually one of the first costs people compare when shopping for affordable health insurance. However, choosing a plan based only on the lowest monthly premium may not always result in the lowest overall healthcare cost.
A lower-premium plan may have a higher deductible or require you to pay more when receiving medical services. A higher-premium plan may reduce some of your costs when you visit doctors or require treatment.
Employer-sponsored plans may also involve contributions from both the employer and employee. Individual and private insurance plans can have different pricing structures depending on age, location, household size, coverage level, and other legally permitted rating factors.
For this reason, it is important to compare the premium alongside the deductible, copayments, coinsurance, provider network, prescription coverage, and potential out-of-pocket expenses.
🧾 Deductible
- 📌 Amount you may pay before certain insurance benefits apply: A deductible is an amount you may need to pay toward eligible healthcare costs before your health insurance begins sharing more of the expenses for certain covered services.
For example, if a health insurance plan has a $1,500 deductible, you may need to pay eligible healthcare expenses up to that amount before certain cost-sharing benefits begin. The exact rules depend on the individual policy.
Not every healthcare service necessarily follows the same deductible rules. Some plans may cover selected preventive services or other benefits differently.
A plan with a higher deductible may have a lower monthly premium, which can be attractive for people who rarely require medical care. However, if unexpected medical treatment is needed, the upfront costs could be higher.
A lower deductible may provide earlier cost-sharing for eligible healthcare services, but the monthly premium could be higher. Comparing both short-term monthly costs and possible healthcare expenses is important.
Before choosing a policy, review which services are subject to the deductible and how the deductible applies to individuals and families.
💵 Copayment
- 🏷️ Fixed payment for specific healthcare services: A copayment, often called a copay, is a fixed amount that you may pay when receiving certain covered medical services.
For example, a health insurance plan may require a specific copayment for a primary care appointment, specialist visit, urgent care service, or prescription medication.
The amount of the copayment can vary depending on the type of service. Visiting a specialist may involve a different copay than visiting a primary care doctor.
Copayments can make healthcare costs easier to predict because you know the approximate amount required for certain covered services.
However, copayment rules are not identical across all health insurance plans. Some services may be subject to a deductible or coinsurance instead.
When comparing health insurance plans, check the policy details to understand how much you could pay for regular doctor visits, specialist appointments, emergency care, and prescription drugs.
📊 Coinsurance
- 📈 Percentage of eligible healthcare costs you may share: Coinsurance is a percentage-based cost-sharing arrangement between you and your health insurance provider.
After applicable deductible requirements have been met, you may be responsible for paying a percentage of the cost of certain covered healthcare services, while the insurance provider pays the remaining eligible portion according to the policy.
For example, a plan may include a coinsurance structure where the insured person pays a specific percentage and the insurer pays the remaining covered amount.
The actual amount you pay can depend on the total cost of the healthcare service. Therefore, coinsurance expenses may be less predictable than a fixed copayment.
Understanding coinsurance is especially important when considering expensive medical procedures, specialist treatment, surgery, or hospitalization.
Always review how coinsurance applies to different services because some plans may use different cost-sharing arrangements depending on whether you receive care from an in-network or out-of-network provider.
🛡️ Out-of-Pocket Maximum
- 🔒 A limit on certain covered costs you may pay yourself: Many health insurance plans include an annual out-of-pocket maximum or a similar spending limit, depending on the healthcare system and policy structure.
This limit generally relates to certain eligible cost-sharing expenses for covered healthcare services. After reaching the applicable maximum, the insurance plan may pay a greater share of additional eligible covered expenses during the policy period.
The exact calculation can vary. Premium payments, non-covered services, and other expenses may not necessarily count toward the applicable limit.
This feature can provide important financial protection in situations involving serious illness, major surgery, hospitalization, or repeated medical treatment.
However, you should carefully review the policy documents because the rules for calculating out-of-pocket expenses can differ between plans.
When comparing insurance policies, consider both the monthly premium and the maximum potential amount you may need to spend on eligible healthcare services.
🏥 What Does Health Insurance Usually Cover?
Health insurance coverage depends on the insurance company, plan type, country, healthcare regulations, and individual policy terms. However, many plans may include a combination of essential healthcare services.
👨⚕️ Doctor and specialist visits:
Health insurance may help cover appointments with primary care physicians and medical specialists. Coverage levels can depend on whether the doctor is included in the plan’s provider network.
Specialist care may require a referral under certain plan structures, while other plans may provide more direct access. Checking these requirements before choosing a plan can help avoid unexpected expenses.
🚑 Emergency medical care:
Emergency healthcare coverage may help with eligible treatment required during serious or unexpected medical situations.
Emergency services can involve ambulance transportation, emergency room treatment, diagnostic testing, hospitalization, and follow-up care. The amount covered depends on the policy terms and applicable regulations.
Because emergencies are unpredictable, reviewing emergency care benefits is an important part of choosing health insurance.
🏨 Hospital treatment:
Hospital care can be one of the most expensive types of healthcare. Health insurance may help cover eligible hospital stays, inpatient treatment, surgery, medical tests, and other approved services.
However, the amount you pay can depend on your deductible, coinsurance, provider network, and policy limitations.
Before enrolling, review how inpatient and outpatient hospital services are covered.
🛡️ Preventive healthcare:
Many health insurance plans provide some form of preventive healthcare coverage. This may include eligible health screenings, vaccinations, routine checkups, and other preventive services.
Preventive care can help identify certain health concerns earlier and support long-term health management.
The availability of specific services depends on your location and health insurance policy.
💊 Prescription medications:
Many insurance plans include prescription drug coverage, but medications may be organized into different pricing levels or formularies.
The amount you pay can vary depending on whether a medication is generic, preferred, non-preferred, or subject to additional requirements.
If you regularly use prescription medication, carefully review the plan’s prescription coverage before enrolling.
🧠 Mental health services:
Some health insurance plans include eligible mental and behavioral healthcare services.
Coverage may include appointments with qualified healthcare professionals, counseling, therapy, or other approved treatment services.
The number of covered visits, provider requirements, and cost-sharing responsibilities can vary significantly between plans and locations.
🤰 Pregnancy and maternity care:
Health insurance may include eligible maternity and pregnancy-related healthcare services depending on the policy and local healthcare system.
Coverage may involve prenatal appointments, medical testing, delivery services, and postnatal care.
People planning a family should carefully compare maternity benefits, waiting periods where applicable, and potential cost-sharing requirements.
🔬 Surgery:
Eligible surgical procedures may be covered according to the terms of the health insurance plan.
Coverage can depend on medical necessity, provider network requirements, preauthorization rules, and other policy conditions.
It is important to understand potential costs before a non-emergency procedure whenever possible.
♿ Rehabilitation services:
Some plans may provide coverage for eligible rehabilitation services, including physical therapy and recovery-related care.
Coverage limits, approved providers, and the number of eligible sessions can vary.
Reviewing rehabilitation benefits may be particularly important for people recovering from injuries, surgery, or major medical treatment.
👶 Pediatric healthcare:
Family health insurance plans may provide healthcare benefits for eligible children, including routine doctor visits, preventive services, vaccinations, and medically necessary treatment.
Parents should review pediatric coverage, specialist access, emergency care, and other child-specific healthcare needs.
🗂️ Types of Health Insurance Plans
There are several types of health insurance plans available, and the best option depends on your country, employment situation, family needs, budget, and healthcare requirements.
👤 Individual Health Insurance
Individual health insurance is designed to provide coverage for one eligible person.
This type of insurance may be useful for freelancers, self-employed professionals, independent contractors, entrepreneurs, or individuals who do not receive health insurance through an employer.
Individual plans can vary significantly in price and coverage. Before selecting a plan, compare the monthly premium, deductible, provider network, prescription benefits, and potential out-of-pocket expenses.
For self-employed individuals, health insurance should be considered as part of the overall personal financial planning process.
👨👩👧👦 Family Health Insurance
Family health insurance can provide coverage for multiple eligible family members under one policy.
Depending on the plan and applicable rules, coverage may include a spouse, partner, children, or other eligible dependents.
Family plans may have different deductible and out-of-pocket structures compared with individual coverage.
When comparing family health insurance, consider the healthcare needs of every covered person. Families with young children, frequent specialist visits, or regular prescription medication requirements may have different priorities than households that rarely require medical care.
A detailed comparison can help identify a policy that offers suitable protection without unnecessary expenses.
💼 Employer-Sponsored Health Insurance
Many employers offer health insurance as part of an employee benefits package.
In some cases, the employer contributes toward the cost of the monthly premium, while the employee pays the remaining portion.
Employer-sponsored coverage can be an important benefit because employer contributions may reduce the direct cost paid by the employee.
However, employees should still review the available plan options carefully. Two employer plans can have very different deductibles, networks, prescription coverage, and cost-sharing structures.
When starting a new job or during an enrollment period, compare the available options based on your expected healthcare needs.
🏛️ Government-Sponsored Health Coverage
Government-supported healthcare programs may provide coverage or financial assistance for eligible individuals.
Eligibility, benefits, enrollment requirements, and available services depend on the country and specific program.
In the United States, several public healthcare programs exist for eligible groups. European countries also operate different public and statutory healthcare systems.
Because eligibility rules can change depending on income, age, employment status, residency, family circumstances, or other legal requirements, always review the current rules that apply in your location.
🏢 Private Health Insurance
Private health insurance is offered by commercial insurance providers and may provide different levels of coverage and provider access.
Some people choose private insurance because they want additional healthcare options, broader provider access, supplementary benefits, or faster access to certain services where available.
Private health insurance policies can differ significantly between the United States and European countries.
Before purchasing private coverage, compare exclusions, waiting periods, deductibles, coverage limits, provider networks, and the policy’s renewal terms.
🔄 HMO vs. PPO: What Is the Difference?
HMO and PPO are two common health insurance network structures, particularly in the United States.
🏥 HMO
An HMO, or Health Maintenance Organization, generally focuses on providing healthcare services through a specific network of doctors, specialists, hospitals, and healthcare facilities.
Members may need to select a primary care provider who helps coordinate their healthcare.
Depending on the plan, a referral may be required before visiting certain specialists.
HMO plans may offer lower costs in some situations, but they can provide less flexibility when choosing healthcare providers outside the network.
Before selecting an HMO plan, check whether your preferred doctors, specialists, and hospitals participate in the network.
🌐 PPO
A PPO, or Preferred Provider Organization, generally offers greater flexibility when choosing healthcare providers.
Members may be able to receive healthcare services without selecting a primary care provider or obtaining referrals in the same way required by some other plan structures.
PPO plans often provide financial advantages when using in-network providers, while out-of-network services may result in higher personal expenses.
Because of the additional flexibility, PPO plans may have higher premiums or other costs.
The right option depends on your budget, healthcare needs, preferred doctors, and willingness to follow provider network requirements.
💰 How Much Does Health Insurance Cost?
The cost of health insurance is not the same for everyone. Prices can vary depending on the plan, location, household, coverage type, and healthcare system.
Several important factors can influence the total cost.
🎂 Your age:
Age can influence health insurance pricing where legally permitted. In some insurance markets, older individuals may face different premium structures because healthcare needs and expected costs can change over time.
Always compare plans using the pricing available for your specific age group and location.
📍 Your location:
Healthcare costs and insurance regulations vary between countries, states, regions, and local markets.
A health insurance plan available in one location may not be available or priced the same way in another area.
For American and European audiences, it is particularly important to understand that national and regional healthcare rules can differ substantially.
📋 The type of plan:
Different plan structures can have different monthly premiums, provider networks, deductibles, and benefit levels.
A plan offering greater flexibility or broader coverage may cost more than a more limited plan.
Compare the complete benefit structure rather than focusing only on the plan name.
👨👩👧 The number of people covered:
Covering multiple family members can increase the total premium.
However, family plans may also provide a more convenient way to manage healthcare coverage for eligible dependents.
Review both individual and family cost-sharing rules when comparing policies.
🧾 Your deductible:
Plans with higher deductibles may have lower monthly premiums in some cases.
However, you could face higher personal costs before the plan contributes significantly toward certain covered services.
Consider how much you could reasonably afford to pay if an unexpected medical event occurs.
⭐ The level of coverage:
More comprehensive plans may provide broader benefits or lower cost-sharing for certain services.
However, additional coverage can also increase the monthly premium.
The best level of coverage depends on your personal healthcare needs and financial situation.
🏥 The provider network:
Plans with larger or more flexible provider networks may have different costs compared with plans that limit coverage to selected healthcare providers.
Always check whether your preferred doctors and hospitals are included.
💶 Available subsidies or employer contributions:
Depending on eligibility and location, financial assistance, subsidies, or employer contributions may reduce the amount you personally pay for health insurance.
These programs can significantly affect the affordability of coverage.
Review current eligibility requirements before making a final decision.
🧭 How to Choose the Best Health Insurance Plan
Choosing the best health insurance plan requires more than selecting the lowest monthly premium. You should compare your expected healthcare needs with the complete cost and coverage structure.
1️⃣ Consider Your Healthcare Needs
- 🩺 Review your expected medical requirements: Start by thinking about how often you normally visit doctors and whether you expect regular healthcare services during the year.
If you frequently visit specialists, a plan with easier specialist access may be important.
People who take regular prescription medications should carefully examine drug coverage.
Families with children may prioritize pediatric care and access to nearby hospitals.
If you rarely need medical services, you may have different priorities from someone managing regular treatment.
Understanding your healthcare needs helps narrow down the available insurance options.
2️⃣ Compare Premiums and Deductibles
- 💰 Look at both monthly and potential healthcare costs: The lowest premium does not always mean the lowest total cost.
A low-premium plan may save money each month but require a larger deductible when medical treatment is needed.
A higher-premium plan may cost more every month while reducing some costs when accessing healthcare.
Consider how often you expect to use medical services and how much financial risk you can manage.
Compare the premium and deductible together instead of viewing them separately.
A balanced comparison can help you avoid choosing a plan that appears inexpensive but becomes costly when you actually need care.
3️⃣ Check the Provider Network
- 🏥 Make sure important healthcare providers are accessible: If you already have a trusted doctor, specialist, clinic, or hospital, check whether it participates in the plan’s provider network.
Receiving treatment outside the network may result in higher costs or reduced benefits, depending on the policy.
A strong provider network can be particularly important for people who require specialist treatment.
Review the availability of healthcare providers near your home or workplace.
For travelers and people who frequently move between regions, access to healthcare outside their primary location may also be an important consideration.
4️⃣ Review Prescription Drug Coverage
- 💊 Check how your medications are covered: Prescription costs can become a major long-term healthcare expense.
Insurance plans may use formularies or medication lists that determine how different drugs are covered.
A medication may require a copayment, coinsurance, prior approval, or the use of a generic alternative.
Before selecting a health insurance plan, check whether the medications you currently use are included.
Also consider how future prescription needs could affect your overall healthcare budget.
A plan with a slightly higher premium may sometimes offer better prescription coverage, depending on your personal needs.
5️⃣ Understand Emergency Coverage
- 🚑 Prepare for unexpected medical situations: Medical emergencies can happen without warning.
A suitable health insurance plan should be reviewed for its emergency room, hospitalization, ambulance, and urgent care coverage.
Check how the policy handles emergency treatment received outside your normal provider network.
This can be particularly important when traveling or living far from your preferred healthcare facilities.
Understanding emergency benefits before an emergency occurs can reduce confusion during a stressful situation.
Always review the specific policy terms because emergency coverage rules differ between plans and healthcare systems.
6️⃣ Compare the Maximum Out-of-Pocket Costs
- 🛡️ Understand your potential financial responsibility: The monthly premium is only one part of the total financial picture.
A serious medical condition or unexpected accident could result in significant healthcare expenses.
Comparing the applicable out-of-pocket maximum can help you understand the potential amount you may need to pay for certain covered healthcare services during the policy period.
Check which expenses count toward this limit and which expenses may be excluded.
This information can be especially valuable for families and individuals who want stronger protection against high medical costs.
A plan should be evaluated based on both everyday affordability and financial protection during major medical events.
🌟 Why Is Health Insurance Important?
Health insurance can provide financial protection and improve access to healthcare services.
💰 Protection from large medical bills:
Unexpected medical emergencies can create expensive bills. Health insurance may reduce the financial impact of eligible healthcare services according to the policy terms.
🏥 Access to healthcare providers:
Insurance coverage may help people access doctors, specialists, hospitals, clinics, and other healthcare services within their plan’s available network.
🔍 Support for preventive care:
Preventive healthcare can help individuals monitor their health and identify certain concerns earlier.
Regular checkups, screenings, and other preventive services may be available depending on the insurance plan and local regulations.
💊 Coverage for eligible prescriptions:
Prescription medication can be expensive, especially when treatment is required over a long period.
Health insurance may help reduce eligible medication costs depending on the policy’s prescription benefits.
🚑 Financial assistance during medical emergencies:
Emergency medical care can involve multiple expensive services, including transportation, testing, treatment, surgery, and hospitalization.
Insurance can provide important financial support for eligible emergency healthcare expenses.
😌 Greater peace of mind:
Knowing that you have health coverage can provide greater confidence when unexpected healthcare needs arise.
While insurance does not eliminate every medical expense, it can help reduce uncertainty and make healthcare costs easier to manage.
💡 How to Save Money on Health Insurance
Finding affordable health insurance requires comparing the complete cost of a plan rather than simply choosing the cheapest monthly premium.
🔎 Compare multiple plans:
Different insurance policies can offer very different benefits at similar price points.
Compare premiums, deductibles, copayments, coinsurance, prescription coverage, and provider networks before choosing.
🏥 Use in-network healthcare providers:
Using doctors and facilities included in your insurance network may reduce your personal healthcare expenses.
Always confirm provider participation because network status can affect coverage.
🩺 Take advantage of eligible preventive services:
Preventive healthcare can help you manage your health before a problem becomes more serious.
Review which preventive services are included in your plan and understand any applicable requirements.
🔄 Review your insurance regularly:
Your healthcare needs can change over time.
Marriage, children, a new job, relocation, or changes in prescription medication may affect which health insurance plan is most suitable.
Reviewing available options during applicable enrollment periods can help ensure your coverage continues to match your needs.
⚠️ Common Health Insurance Mistakes to Avoid
Choosing health insurance without reviewing the complete policy can result in unexpected costs.
❌ Ignoring the deductible:
A low monthly premium may look attractive, but a high deductible could create significant expenses when you require medical treatment.
Always consider how much you could realistically afford to pay.
❌ Not checking the provider network:
Your preferred doctor or hospital may not be included in every insurance plan.
Checking the network before enrollment can help prevent unexpected out-of-network costs.
❌ Forgetting to review prescription coverage:
Prescription medications can create recurring expenses.
Reviewing drug coverage before choosing a plan is especially important if you use regular medication.
❌ Choosing a plan without understanding the out-of-pocket costs:
Premiums represent only part of your potential healthcare spending.
Deductibles, copayments, coinsurance, and applicable out-of-pocket limits should also be compared.
❌ Assuming all medical services are automatically covered:
Health insurance policies have specific coverage rules.
Some services may have exclusions, limitations, prior authorization requirements, or network restrictions.
❌ Not reading exclusions and limitations:
Policy documents contain important information about what is and is not covered.
Reading these details can help prevent misunderstandings later.
❌ Failing to compare multiple available options:
Choosing the first plan you see may mean missing a better option.
Compare several available plans based on your healthcare needs, budget, provider preferences, and expected medical expenses.
📝 Frequently Asked Questions About Health Insurance
❓ What is the best health insurance plan?
The best health insurance plan depends on your location, healthcare needs, budget, preferred doctors, prescription requirements, and the plans available to you. There is no single health insurance policy that is best for every individual or family.
❓ Is a low-premium health insurance plan always cheaper?
No. A lower monthly premium can sometimes be combined with a higher deductible, higher copayments, or greater coinsurance. Compare the total potential cost of the plan, especially if you expect to use healthcare services regularly.
❓ Can I use any doctor with health insurance?
That depends on your insurance plan and provider network. Some plans limit coverage to specific healthcare providers, while others may offer greater flexibility. Using an out-of-network provider can result in higher costs or reduced coverage.
❓ What should I compare before choosing health insurance?
You should compare the monthly premium, deductible, copayments, coinsurance, applicable out-of-pocket maximum, provider network, prescription drug coverage, emergency benefits, exclusions, and policy limitations.
❓ What is the difference between an HMO and PPO?
An HMO generally uses a more structured provider network and may require a primary care provider or referrals for certain specialist services. A PPO typically provides greater flexibility when choosing healthcare providers but may involve higher premiums or costs.
❓ Is private health insurance available in Europe?
Yes, private health insurance is available in many European countries. However, its role varies depending on the country’s public healthcare or statutory insurance system. Private insurance may supplement public coverage or provide additional benefits depending on the country and policy.
❓ How can I find affordable health insurance?
Compare multiple plans and evaluate the total cost, not just the monthly premium. Consider deductibles, copayments, prescription benefits, provider networks, and any financial assistance or employer contributions for which you may be eligible.
❓ Does health insurance cover emergency treatment?
Many health insurance plans provide coverage for eligible emergency medical treatment, but the exact level of coverage depends on the plan, provider network rules, location, and policy terms. Review your policy’s emergency care section for specific details.
🏁 Final Thoughts
Health insurance is an important part of financial planning and healthcare access for individuals and families in the United States and Europe. A suitable insurance policy can help manage eligible medical expenses and provide greater financial protection when unexpected healthcare needs arise.
However, the best health insurance plan is not necessarily the one with the lowest monthly premium.
Before choosing coverage, compare your premium, deductible, copayments, coinsurance, provider network, prescription drug benefits, emergency coverage, exclusions, and potential out-of-pocket expenses.
Your healthcare needs, financial situation, family size, and location should all influence your decision. Taking time to understand the details of a health insurance policy can help you make a more informed choice and avoid unexpected healthcare costs in the future.