📖 Introduction
Saving money fast on a low income has become increasingly challenging in 2026 because of rising inflation, higher rent prices, expensive groceries, healthcare costs, transportation expenses, and ongoing economic uncertainty across the United States and Europe. Many individuals and families struggle to manage basic living expenses while also trying to build savings for emergencies, future goals, or debt reduction.How to Save Money Fast on a Low Income (Complete 2026 Guide)
Despite these financial pressures, saving money is still possible even with limited income. Building financial security is not always about earning a large salary. In many cases, it depends more on smart budgeting, disciplined spending habits, financial awareness, and consistent money management. Small changes in daily financial behavior can create significant long-term improvements over time.
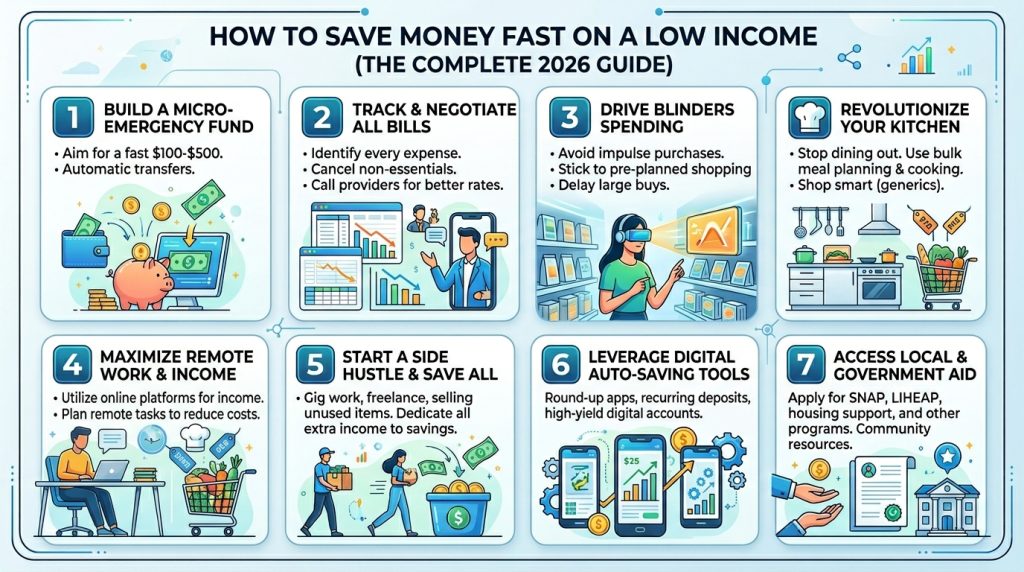
Modern financial planning focuses on reducing wasteful spending, increasing savings efficiency, controlling debt, and creating sustainable financial habits that support long-term stability. This complete semantic SEO guide explains how to save money fast on a low income in 2026 using practical budgeting strategies, expense reduction techniques, emergency fund planning, debt management methods, and smart financial habits.
Table of Contents
📊 Understand Your Financial Situation First
Understanding your financial situation is the first step toward saving money effectively. Many people struggle financially because they do not fully understand where their income is being spent each month.
📈 Track Monthly Income and Expenses:
Tracking monthly income and expenses improves financial awareness and helps identify unnecessary spending patterns that may prevent effective saving. Many individuals underestimate how much money is lost through recurring subscriptions, fast food purchases, entertainment expenses, online shopping, and daily impulse spending. Recording every expense creates accountability and helps households understand exactly where money is going each month. Financial tracking also reveals opportunities for reducing costs and reallocating funds toward savings goals. Many successful budgeters use spreadsheets, budgeting apps, or financial journals to organize their expenses more efficiently. Consistent monitoring of income and spending strengthens money management skills and helps prevent financial waste. Understanding financial behavior is essential for creating long-term stability and improving saving habits on a limited income.
💵 Identify Essential vs Non-Essential Spending:
Separating essential expenses from non-essential spending is critical for improving financial control and reducing unnecessary costs. Essential expenses generally include rent, utilities, transportation, healthcare, groceries, insurance, and minimum debt payments. Non-essential spending often includes luxury shopping, expensive dining, entertainment subscriptions, impulse purchases, and lifestyle upgrades that can be reduced or delayed temporarily. Understanding the difference between needs and wants allows individuals to prioritize survival expenses while creating room for savings and debt repayment. Many people improve their financial situation significantly simply by reducing lifestyle inflation and avoiding unnecessary purchases. This strategy helps individuals focus on long-term financial security instead of short-term convenience or emotional spending habits.
📉 Analyze Spending Habits:
Analyzing spending habits helps identify emotional or impulsive financial behavior that may slow financial progress. Some individuals spend money because of stress, boredom, social pressure, or emotional comfort without realizing the long-term financial consequences. Reviewing bank statements and budgeting reports can reveal recurring expenses that no longer provide meaningful value. Understanding financial behavior improves self-control and encourages healthier spending decisions during difficult economic periods. Individuals who recognize emotional spending patterns are more likely to avoid unnecessary debt and maintain stronger financial discipline. Financial awareness is one of the most important foundations of successful money management and sustainable saving strategies.
💰 Create a Realistic Budget
Budgeting remains one of the most effective methods for saving money quickly because it gives every dollar a purpose and reduces financial waste.
📊 Use the 50/30/20 Budget Rule:
The 50/30/20 budgeting strategy divides income into three major categories: essential needs, personal wants, and savings or debt repayment. Approximately 50% of income is allocated toward necessities such as housing, groceries, transportation, insurance, and utilities. Around 30% is used for personal spending and entertainment, while the remaining 20% supports savings goals or debt reduction. Individuals with lower income may need to adjust these percentages by reducing optional spending and focusing more heavily on essentials. Budgeting structures help create financial balance and improve spending discipline. Consistently following a realistic budget can strengthen financial stability, reduce stress, and accelerate savings growth over time.
🛡️ Build Spending Discipline:
A budget is only effective when financial discipline is maintained consistently. Spending discipline means avoiding impulse purchases, reducing emotional spending, and staying focused on long-term financial goals rather than short-term satisfaction. Many people struggle financially because they spend without planning carefully or tracking purchases properly. Building disciplined financial habits requires patience and consistency, but these habits become easier with practice over time. Financial discipline also improves confidence because individuals feel more in control of their money and better prepared for emergencies. Responsible budgeting supports stronger savings habits, reduces financial stress, and improves overall financial health.
💵 Set Achievable Savings Goals:
Realistic savings goals help maintain motivation and create measurable financial progress. Instead of focusing only on extremely large financial targets, many experts recommend starting with smaller milestones such as building a one-month emergency fund or paying off a small debt balance. Achievable goals make saving feel manageable even for individuals with limited income. Reaching smaller goals also builds confidence and encourages continued financial discipline. Gradually increasing savings targets over time creates momentum and improves long-term financial stability. Clear savings objectives help individuals stay focused during difficult financial situations and reduce unnecessary spending temptations.
🛒 Reduce Grocery and Food Expenses
Food expenses are one of the largest monthly costs for many households, making grocery budgeting an important money-saving strategy.
🥦 Plan Meals in Advance:
Meal planning is one of the most effective methods for reducing food expenses and avoiding unnecessary restaurant spending. Preparing meals at home is usually much cheaper than ordering takeout or eating at restaurants frequently. Planning weekly meals also improves grocery shopping efficiency because purchases are based on actual needs instead of impulse decisions. Many households save hundreds of dollars monthly simply by cooking at home consistently and reducing food waste. Meal preparation also supports healthier eating habits because homemade meals often contain fewer processed ingredients and lower costs. Organized meal planning helps maximize grocery budgets while improving financial stability and nutritional quality.
🛍️ Buy Generic Brands:
Generic or store-brand products are often significantly cheaper than premium brands while offering similar quality and functionality. Choosing affordable alternatives for groceries, household supplies, medications, and cleaning products can reduce monthly expenses substantially over time. Smart consumers focus on product value instead of brand popularity when managing tight budgets. Small savings on regular purchases accumulate quickly and contribute meaningfully to emergency funds or debt repayment goals. Financially disciplined shoppers compare prices carefully and avoid paying extra simply for advertising or packaging. This strategy helps households reduce expenses without sacrificing quality of life.
🚫 Avoid Impulse Grocery Purchases:
Shopping without a grocery list often leads to overspending and unnecessary purchases. Grocery stores are specifically designed to encourage impulse buying through promotions, emotional marketing, and strategic product placement. Creating a detailed shopping list and following it carefully helps reduce waste and control spending. Avoiding unnecessary snacks, luxury items, and convenience foods can significantly lower monthly grocery costs. Financial discipline during grocery shopping remains one of the simplest yet most effective methods for saving money quickly. Many low-income households improve financial stability dramatically by reducing emotional shopping habits and focusing only on essential purchases.
💳 Pay Off High-Interest Debt Quickly
High-interest debt can prevent financial growth because a large portion of income goes toward interest payments instead of savings or investments.
📉 Focus on High-Interest Balances First:
Paying off credit cards and loans with the highest interest rates reduces long-term financial pressure and improves monthly cash flow. High-interest debt grows rapidly over time and can trap individuals in ongoing financial stress if left unmanaged. Eliminating expensive debt frees more income for savings, emergency funds, and essential living expenses. Many financial experts recommend prioritizing debt repayment before making large investments because interest costs often outweigh investment returns. Reducing debt also improves credit scores and strengthens long-term financial flexibility.
💵 Avoid New Unnecessary Debt:
Avoiding additional borrowing is essential for improving financial health on a low income. Many individuals rely on credit cards for non-essential purchases, which creates long-term repayment problems and financial stress. Developing disciplined spending habits and living within realistic financial limits helps prevent future debt accumulation. Responsible debt management improves financial confidence and creates more opportunities for saving and investing over time. Financial freedom becomes easier to achieve when unnecessary borrowing is reduced significantly.
🛡️ Build Financial Freedom Gradually:
Reducing debt creates greater financial freedom because more income becomes available for savings, emergency planning, and future investments. Becoming debt-free also reduces stress and improves overall financial security. Long-term financial independence becomes easier when income is no longer consumed by recurring interest payments and loan obligations. Individuals who consistently reduce debt while building savings often experience stronger financial confidence and improved quality of life. Financial freedom is achieved gradually through disciplined budgeting and responsible money management habits.
📌 Final Thoughts
Saving money fast on a low income in 2026 requires discipline, strategic planning, and consistent financial habits rather than extremely high earnings. Individuals and families across the United States and Europe can improve financial stability by tracking expenses carefully, creating realistic budgets, reducing unnecessary spending, managing debt responsibly, and prioritizing long-term financial goals.
Building savings may feel slow initially, but small consistent improvements create meaningful financial progress over time. Developing smarter spending habits, reducing financial waste, and maintaining disciplined budgeting practices can help create emergency savings, reduce financial stress, and improve long-term financial security even during challenging economic conditions.
❓ Frequently Asked Questions (FAQs)
💬 How can I save money quickly on a low income?
You can save money faster by creating a strict budget, reducing unnecessary expenses, cooking at home, avoiding impulse purchases, and paying off high-interest debt.
💬 What is the best budgeting method for low-income households?
The 50/30/20 budgeting strategy is widely recommended, but low-income households may need to prioritize essentials and savings more aggressively.
💬 Is it possible to build an emergency fund with limited income?
Yes. Small consistent savings over time can gradually build a reliable emergency fund even with limited income.
💬 How can I reduce grocery expenses effectively?
Meal planning, buying generic brands, using shopping lists, and cooking at home can significantly reduce grocery spending.
💬 Should I save money or pay off debt first?
High-interest debt should usually be prioritized because interest payments can slow long-term financial progress significantly.
💬 Why is budgeting important for saving money?
Budgeting improves spending awareness, reduces financial waste, controls unnecessary expenses, and helps individuals achieve savings goals effectively.
💬 Can low-income individuals achieve financial stability?
Yes. Financial stability is possible through disciplined budgeting, responsible debt management, consistent saving habits, and smart financial planning.
💬 What are the biggest mistakes people make when trying to save money?
Common mistakes include impulse spending, emotional shopping, ignoring budgets, carrying high-interest debt, and failing to track expenses consistently.